


CBDT Introduces New Form for Tax Exemption on Government Securities

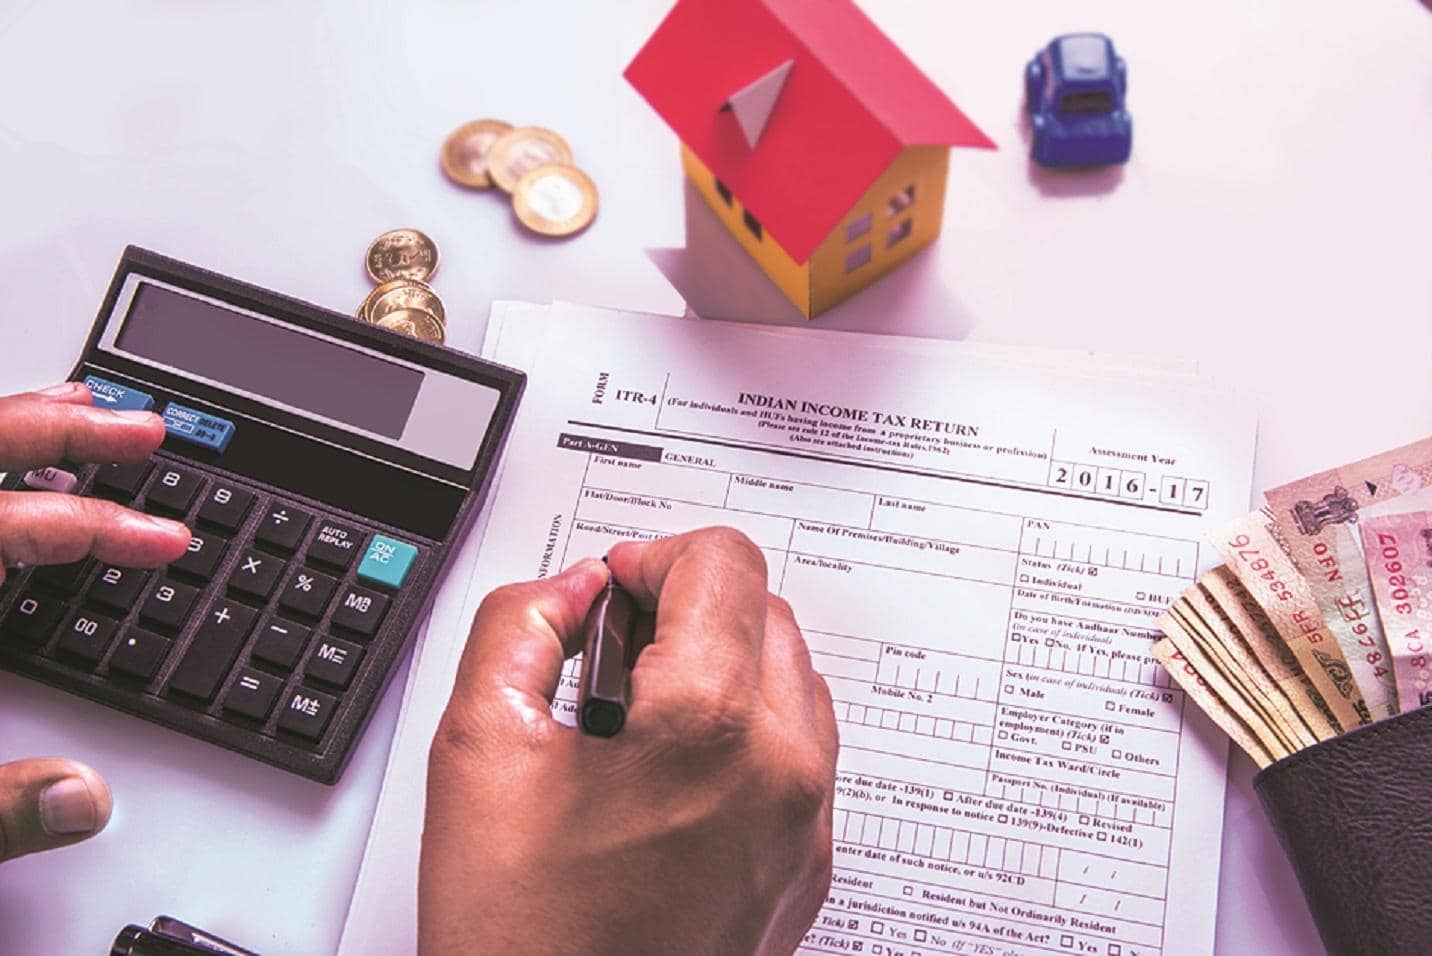


The Central Board of Direct Taxes (CBDT) has unveiled a new form that taxpayers must submit to claim income-tax exemptions on earnings from government securities. This development was formalized through the notification of the Income-tax (Seventh Amendment) Rules, 2026, issued on October 19.




The newly introduced Form 173A serves as the official document for investors to declare income eligible for exemption under entries 13D and 13E of Schedule IV of the Income-tax Act, 2025. These provisions grant tax relief on interest income and capital gains derived from government securities, including scenarios involving sale, exchange, or transfer of such assets.
Entry 13D specifically applies to foreign institutional investors (FIIs), while entry 13E pertains to the Bank for International Settlements (BIS). It is important to highlight that these exemptions do not extend to ordinary investors, focusing instead on these particular categories.
Form 173A requires comprehensive information from taxpayers. Basic identification details must be provided, such as the taxpayer’s full name, country of residence, residential address, Permanent Account Number (PAN), and tax identification number corresponding to their country of residence. Additionally, foreign portfolio investors (FPIs) or FIIs need to supply their Securities and Exchange Board of India (SEBI) registration number. Contact information including email and phone number is also mandatory.
Beyond personal details, the form demands specific transaction-related data for each government security held. This includes the International Securities Identification Number (ISIN), the type of security (which could be Treasury Bills, fixed-rate bonds, floating-rate bonds, State Development Loans or SDLs, among others), tenor, and the valuation of securities as of April 1 of the tax year.
Taxpayers must also disclose the value of securities acquired during the year, the sale consideration received from securities sold, total holdings as of March 31, gross interest income either received or accrued during the financial year, and capital gains realized in the same period.
A declaration confirming the accuracy and truthfulness of the information submitted is a required part of Form 173A. This statement must be signed by the principal officer responsible for the submission. Notably, the notification clarifies that for the Bank for International Settlements, providing the tax identification number and SEBI registration number is optional.
The Income-tax Rules, 2026, initially came into effect on March 20, 2026, with several amendments introduced since then, reflecting evolving regulatory requirements. This latest amendment and the introduction of Form 173A further streamline the process of claiming exemptions on government securities, ensuring better compliance and transparency.
Government securities have long been viewed as a stable investment option, offering regular interest payments backed by sovereign guarantees. These exemptions are designed to encourage participation from foreign investors and institutions like BIS by offering tax benefits aligned with international financial norms.
For foreign institutional investors, such tax relief can significantly impact the after-tax returns on government securities, making these instruments more attractive. Similarly, the BIS benefits from eased tax obligations, supporting its role in global financial stability.
Investors and institutions affected by these changes should prepare to furnish the newly required details promptly, adhering to the timelines set by the tax authorities. This adjustment in reporting procedures highlights the government’s ongoing efforts to refine tax administration and promote clarity in financial disclosures.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0












Comments (0)