


India’s Small Finance Banks Expand Outreach but Credit Shortfall Persists




Small finance banks (SFBs) in India have made notable strides over the past decade in bringing previously underserved customers into the formal banking network. Despite this progress, the sector still faces a significant gap in meeting the country’s credit needs, according to senior industry executives speaking at the Business Standard BFSI Insight Summit 2026.




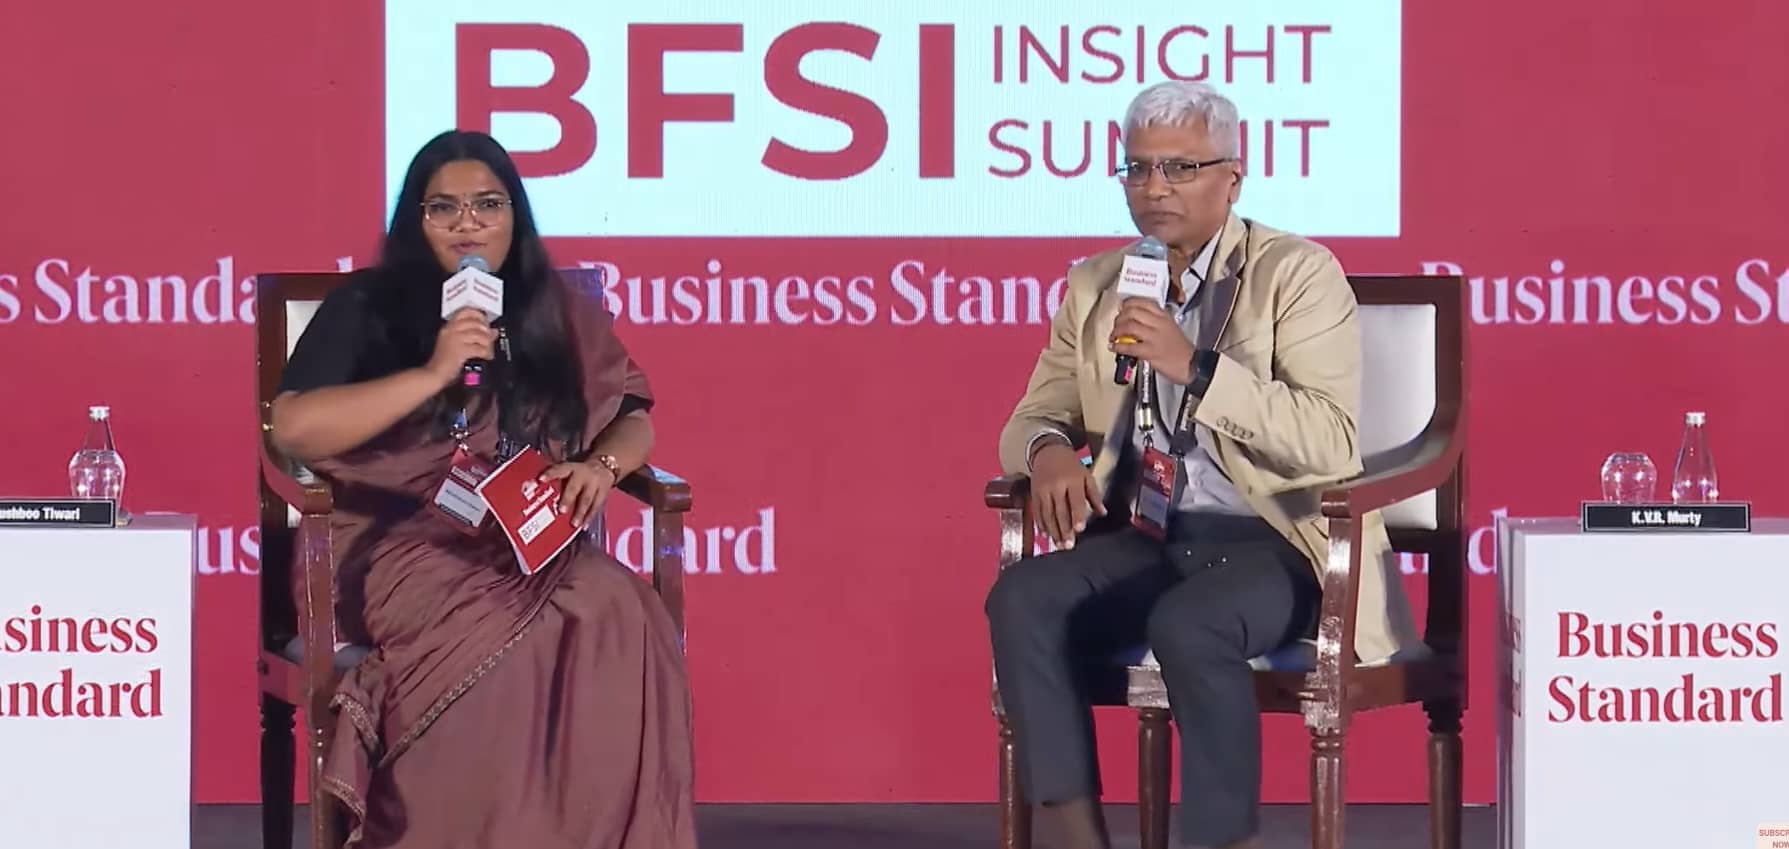
During a panel discussion titled ‘Small finance banks: Mandate fulfilled- Universal bank next?’, P N Vasudevan, Managing Director and CEO of Equitas Small Finance Bank, and Baskar Babu Ramachandran, MD and CEO of Suryoday Small Finance Bank, weighed in on the sector’s achievements, the hurdles in acquiring universal banking licenses, and the future outlook for microfinance.
Financial Inclusion Progress and Remaining Challenges
Vasudevan highlighted that the estimated unmet credit demand among informal and semi-formal borrowers in India is approximately ₹85 trillion, which accounts for nearly one-third of the country’s total banking credit. He emphasized the enormity of this figure by pointing out that the current eleven small finance banks would require about 65 years to fully meet this demand, assuming they maintain a 15 percent compound annual growth rate and the unmet demand does not increase with inflation.
"The financial inclusion mandate is far from being complete," Vasudevan said. However, he acknowledged the considerable progress individual SFBs have made in extending banking services to customers who were previously excluded from formal finance. Although small finance banks contribute about 1.5 percent to total banking credit, they serve close to 10 percent of banking customers, showcasing their role in reaching underserved populations.
Ramachandran added that financial inclusion should not be measured solely by lending volume. Small finance banks have also played a crucial role in expanding access to savings accounts and other financial products. Their services have grown beyond microfinance to include affordable home loans and small-ticket vehicle loans. The next frontier, he explained, is to help customers transition from borrowing small amounts to accessing a broader range of financial services.
Universal Banking Licenses: A Path Forward
The panelists agreed that obtaining universal banking licenses represents a logical next step in the evolution of small finance banks, though this transition involves regulatory hurdles and concerns about deposit costs.
Ramachandran mentioned that the label “small finance bank” might create perceptions of higher risk among depositors, potentially raising the cost of deposits despite the sector’s decade-long track record. Vasudevan noted that SFBs are already subject to regulatory requirements similar to those of universal banks, including cybersecurity measures, anti-money laundering systems, and transaction monitoring.
Capital adequacy standards differ, however. Small finance banks must maintain a minimum capital adequacy ratio of 15 percent, while universal banks have a base requirement of 9 percent before considering additional buffers. Vasudevan described the move to a universal bank license as a natural stage in the sector’s maturity.
While the Reserve Bank of India has set out criteria for SFBs seeking to convert to universal banks, meeting these standards does not guarantee approval. The regulator evaluates overall performance, compliance culture, operational systems, and supervisory comfort. Consistent financial performance is a key factor before banks submit their applications, according to Vasudevan.
Microfinance Sector and Risk Management
The panel also addressed the recent challenges facing the microfinance industry. Vasudevan shared that the sector’s portfolio has shrunk from around ₹4.6 trillion to ₹3.5 trillion over the past 18 months, a decline of about 25 percent. This reduction indicates that the problem of excessive borrowing has lessened, though some instances of overleveraging remain.
He pointed out the difficulties lenders face in identifying borrowers who have taken multiple loans from different institutions due to gaps in credit bureau data. Ramachandran observed that unlike earlier crises that were regionally contained, the latest troubles affected borrowers across several states. He called for improved risk management and more disciplined lending practices.
Future Outlook and Sector Consolidation
Regarding potential mergers and acquisitions, Vasudevan stated that consolidation will depend on banks’ ability to create lasting value for shareholders and stakeholders alike. Ramachandran emphasized that banking is a long-term endeavor and cautioned against expecting rapid growth, highlighting the importance of building sustainable institutions over time.
Small finance banks have become an important part of India’s financial ecosystem by expanding access to credit and other banking services among underserved communities. Yet, the sector continues to grapple with large unmet credit demand and the complexities involved in scaling operations and regulatory compliance. The evolution toward universal banking licenses and strengthened risk controls will likely shape the future trajectory of these banks as they seek to deepen financial inclusion across the country.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0













Comments (0)