


India's Hotel Investments Soar 197% with Focus on Tier II and III Cities

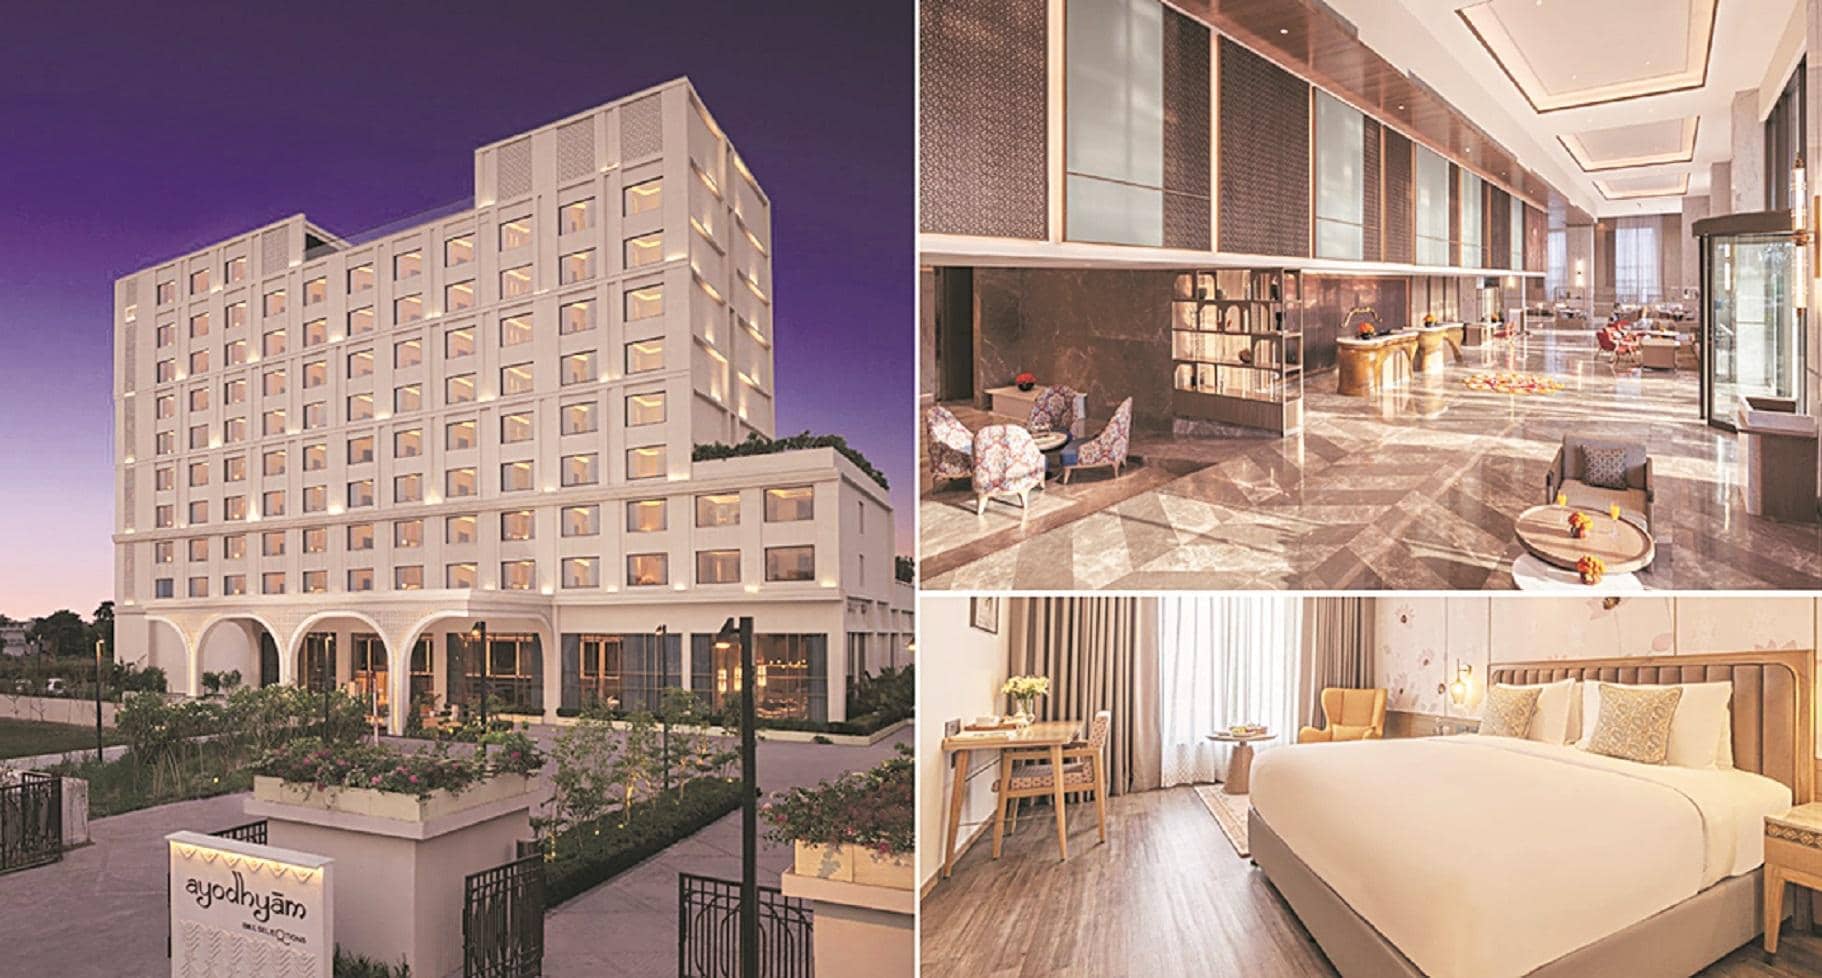


India’s hotel investment sector experienced remarkable growth in the first half of 2026, with total transactions reaching $497 million from 11 deals. This represents a 197% rise compared to $167 million during the same period in 2025, according to a recent analysis by property consultancy JLL. The full-year transaction volume is expected to hit $1.1 billion, nearly doubling the $567 million recorded in 2025.




A notable shift in investor composition has emerged. Real estate developers dominated the market in early 2026, accounting for 58% of transaction volumes. This is a significant change from 2025, when high-net-worth individuals (HNIs), family offices, and private hotel owners collectively held more than half of the investment share. Listed hotel companies contributed 31.1% of transactions in the first half, while HNIs and family offices combined for just 8.2%. JLL’s managing director for Hotels in India, Gaurav Sharma, highlighted this transformation as a fundamental reshaping of capital flows into hospitality assets, driven by India's expanding tourism and consumer base.
Investment activity has notably shifted towards India’s smaller cities. Tier II and III locations captured 60% of the hotel investment volume, reflecting growing interest beyond the traditional Tier I metros, which accounted for the remaining 40%. Deals involved luxury resorts in Kerala and Coorg, luxury hotels in Agra, Mussoorie, and Noida, as well as upper-upscale properties in Udaipur and Jaipur. This trend is supported by increased demand for leisure destinations and emerging markets becoming attractive for investors.
The development pipeline aligns with these investment patterns. Of the 29,360 branded hotel keys signed in the first six months of 2026, 74% were in Tier II and III cities. This includes established tourist spots like Rishikesh and Jaipur, along with emerging markets such as Patna and Navi Mumbai. In the latter half of the year, acquisitions continued in cities like Ahmedabad, Bengaluru, and Pune. JLL also noted strategic land deals covering 420 acres in the Mumbai Metropolitan Region and 15 acres in Goa, valued together at around $313 million.
Distressed asset transactions played a significant role, making up 58% of the total volume. These deals, linked to the Insolvency and Bankruptcy Code (IBC), amounted to roughly $288 million. Such acquisitions present opportunities to obtain existing hotel properties, though risks remain related to property conditions and repositioning costs. Operational hotels dominated the market, accounting for about 70% of transactions, while under-construction or non-operational properties made up 23%. The remainder involved land leases.
Investor preference showed a clear tilt toward higher-end assets. Luxury hotels comprised 51% of the investment volume, followed by upscale properties at 35%, upper-upscale hotels at 12%, and economy hotels at 2%. This distribution suggests a focus on well-established and operational assets with strong return potential.
Branded hotel signings surged to 29,360 keys during the first half of 2026. Management contracts represented the majority, at 77%, with franchise agreements contributing 22%, and lease or revenue-share models making up 1%. Greenfield projects accounted for 13,689 keys, signaling ongoing expansion in new hotel supply. The signing of large-scale hotels with more than 250 keys also increased, with 15 such properties signed compared to five in the first half of 2025. New hotel openings added 5,048 branded keys, 71% of which were in Tier II and III cities. The upscale segment led openings at 45%, followed by midscale at 28%, economy at 14%, upper-upscale at 8%, and luxury at 5%.
Looking ahead, JLL forecasts that hotel investment momentum will continue through the rest of 2026. The projected full-year volume of $1.1 billion would mark a 94% increase over 2025. Investors are expected to maintain focus on high-quality branded hotels with strong operational performance in both established and emerging destinations. Platform-level investments may gain prominence as institutional investors seek scale and diversified exposure across multiple markets.
The surge in hotel investment reflects broader trends in India’s hospitality industry, driven by rising domestic tourism, evolving consumer preferences, and urbanization. The growing appeal of Tier II and III cities highlights the shifting landscape where smaller cities offer attractive growth prospects and value. Meanwhile, distressed asset transactions under the IBC provide avenues for acquiring assets at favorable entry points, supporting the continued expansion of the sector.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0












Comments (0)