


RBI’s New Measures May Ease Rupee Pressure but Won’t Halt Decline



The Reserve Bank of India (RBI) introduced several measures over the past weekend aimed at reducing the rupee’s recent slide against the US dollar. While these moves could help alleviate immediate stress in the spot market and lower forward premiums, analysts caution that they are unlikely to reverse the currency’s broader weakening trend driven by external factors.




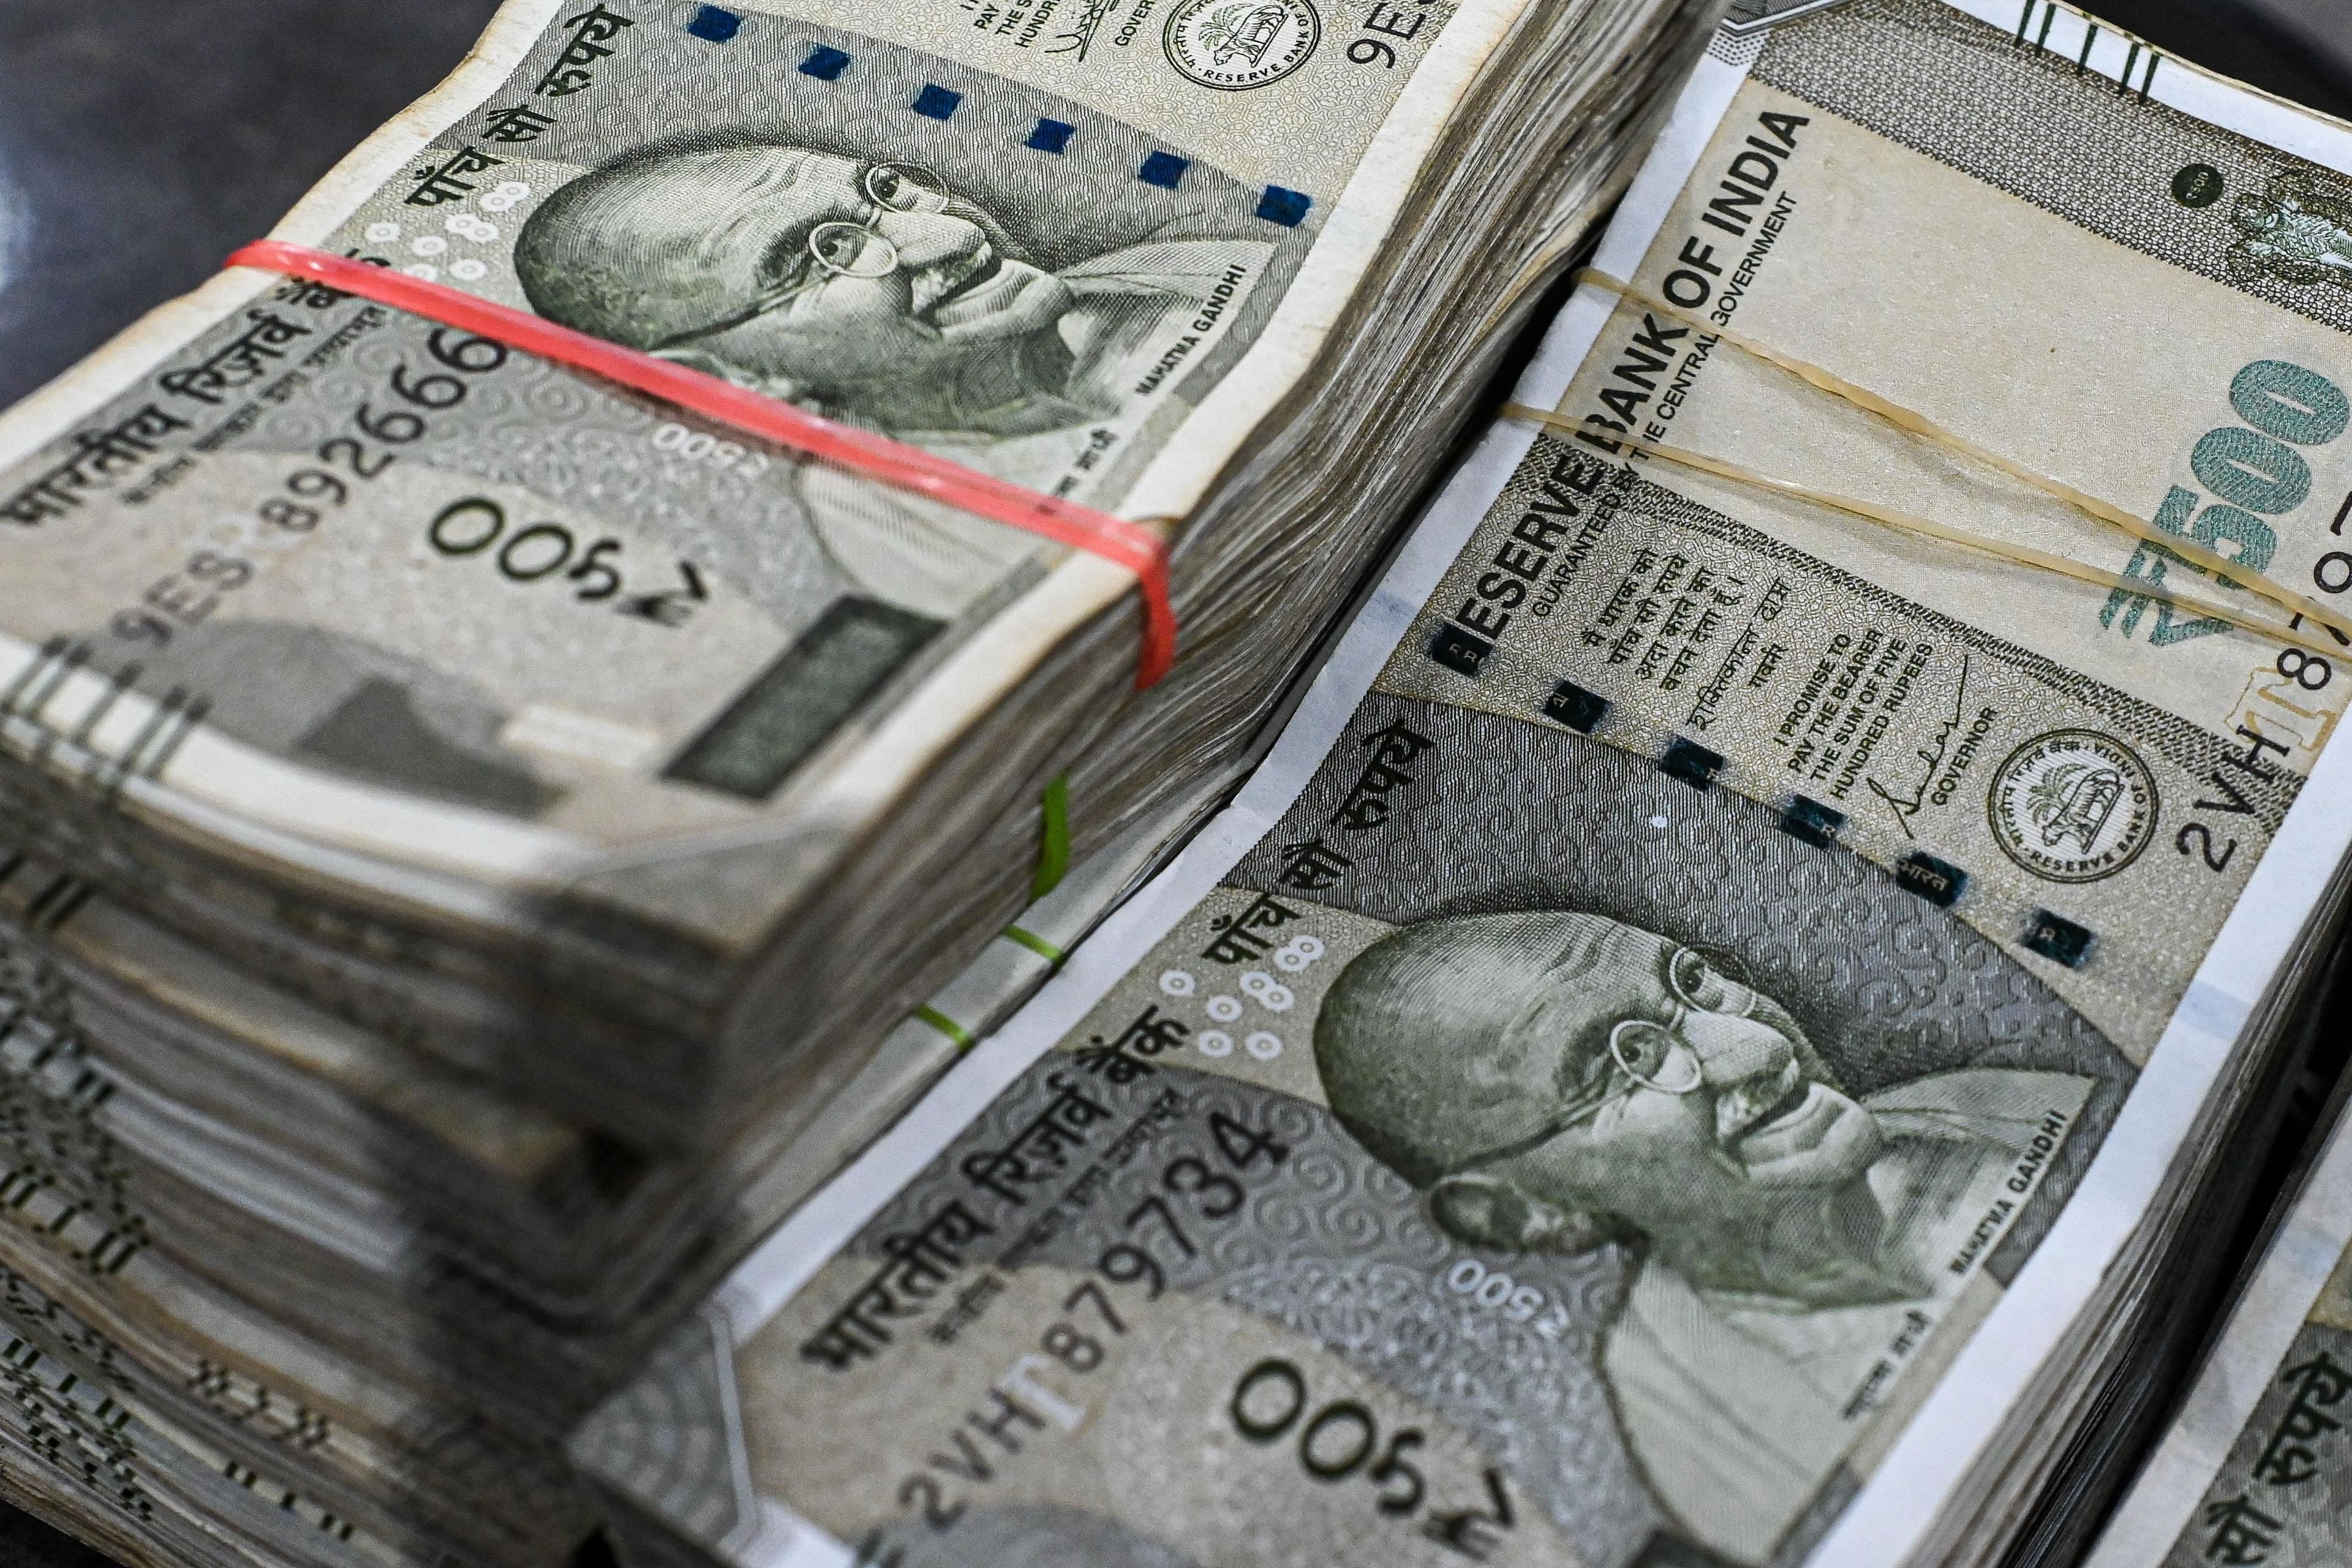
On Friday, the rupee ended trading at 96.73 per dollar, close to its record low of 96.96 reached on May 20, 2026. In response to the ongoing depreciation, the RBI announced a dedicated dollar window specifically for three state-run oil marketing companies (OMCs) and tightened regulations on foreign exchange derivatives to curb speculative activity and reduce demand for dollars connected to hedging.
Gaura Sen Gupta, chief economist at IDFC First Bank, commented, "These measures are expected to result in near-term reduction in USD-INR as well as lower forward premiums." However, she added that medium-term currency movements will still depend on global economic conditions and India’s balance of payments, factors likely to continue exerting depreciation pressure. "The RBI’s actions will slow the pace of decline but will not stop it," she noted.
Since the onset of the West Asia conflict on February 28, 2026, the rupee has lost approximately 6 percent, accumulating to over 7 percent year-on-year. The combination of elevated crude oil prices, a strong US dollar, high global bond yields, and subdued capital flows has created a challenging environment for the currency. These dynamics have kept the rupee near the psychologically significant 97-per-dollar level.
A treasury head at a private bank highlighted the limits of RBI’s recent steps, stating, "These measures will help for now, but they don’t fix what is driving the rupee lower. Crude oil prices remain high, the dollar is strong, global yields are elevated, and our balance of payments is weak. Until these underlying issues shift, the rupee will stay under pressure."
The RBI’s special dollar window, effective from October 12, will cater to the entire daily dollar needs of Indian Oil Corporation (IOC), Hindustan Petroleum Corporation (HPCL), and Bharat Petroleum Corporation (BPCL). Market experts estimate that public-sector OMCs account for about $10 billion to $12 billion in monthly oil-related dollar demand, or roughly $300 million to $400 million daily. By channeling these purchases through the RBI, the central bank aims to reduce dollar demand in the open market, thereby easing pressure on the rupee.
Kotak Mahindra Bank noted in a report that while a portion of this demand involves forward contracts, the RBI’s separate window should remove a significant amount of spot dollar demand from the market.
Alongside this, the RBI has imposed restrictions on rebooking canceled rupee-linked foreign exchange derivative contracts, whether deliverable or non-deliverable. It has also lowered the threshold for transactions that hedge contracted exposures without requiring proof of underlying exposure from $100 million to $5 million, calculated across all authorized dealers. The objective is to deter speculative positions formed without genuine exposure, though this does not eliminate speculative activity entirely.
Similar limits apply to rupee-linked exchange-traded currency derivatives on recognized exchanges, with transactions above the threshold requiring additional documentation. The $5 million threshold, however, does not cap genuine hedging transactions overall.
Another notable addition is the Foreign Exchange Risk Reserve (FERR) requirement. Under this rule, authorized dealers must maintain cash reserves with the RBI equivalent to 20 percent of the rupee value of specified derivative contracts where users buy foreign currency against the rupee and where the notional contract value exceeds $2 million. Sen Gupta explained, "During periods of sustained rupee depreciation, importers tend to increase hedging while exporters reduce it, creating an imbalance in dollar demand. The FERR aims to address this by acting like a foreign exchange cash reserve ratio."
This reserve requirement could lead to higher hedging costs as banks pass on the increased cost of funds to clients, potentially reducing demand for forward covers and easing forward premiums. The impact may differ between importers hedging actual payment obligations and those entering speculative transactions without underlying exposure.
The RBI’s latest interventions build on previous efforts to stabilize the currency. In August 2013, it created a similar special window for the same three oil companies to meet their dollar needs through dollar-rupee swaps. More recently, in March 2026, the central bank capped banks’ net open dollar-rupee positions at $100 million in the onshore deliverable market and tightened client access to non-deliverable forward contracts.
Given the current global economic backdrop, including geopolitical tensions, commodity price volatility, and shifts in capital flows, the rupee’s trajectory will remain sensitive to external factors. RBI’s measures may provide some breathing space in the currency market but are unlikely to fully offset broader pressures weighing on the rupee.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0












Comments (0)