


NSE Lists Shares on BSE After 34 Years, Redefines Indian Stock Markets

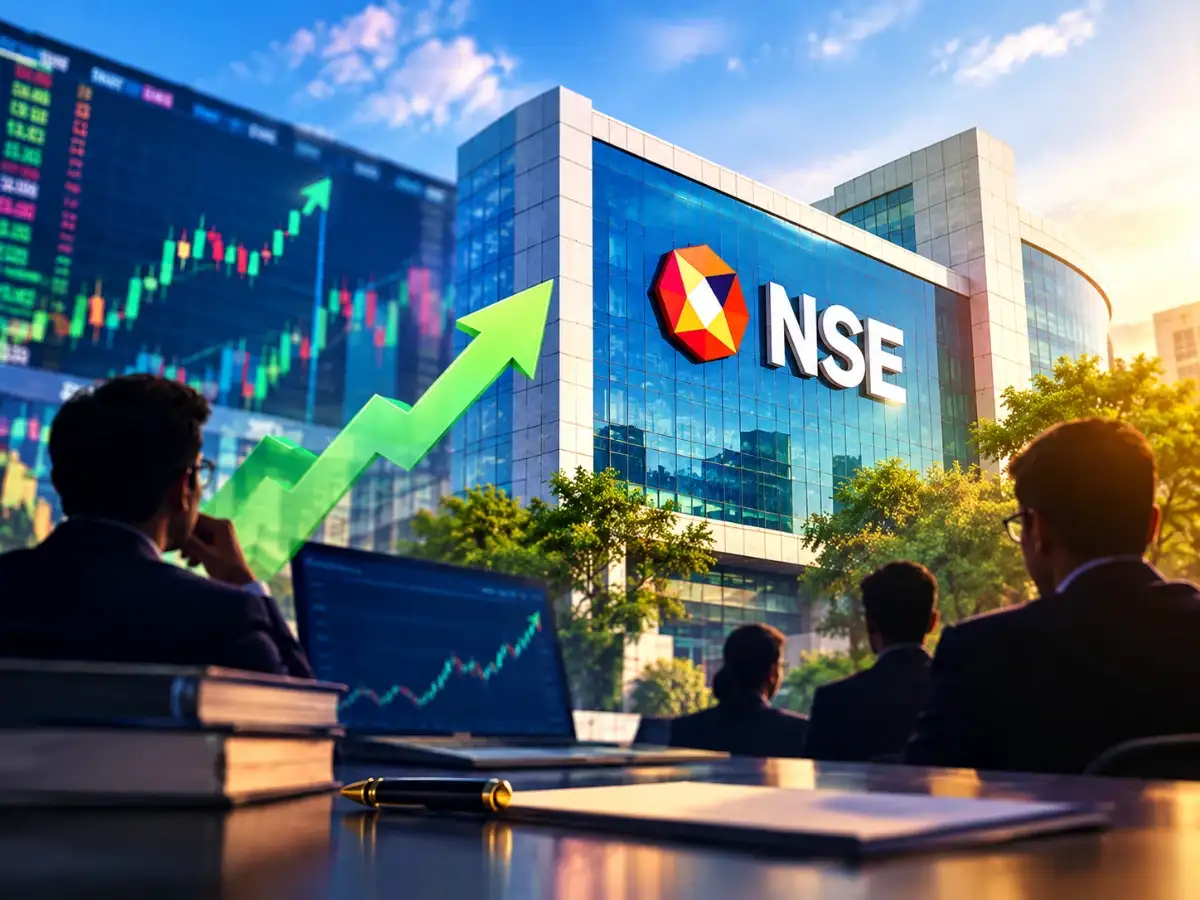


After more than three decades since its establishment, the National Stock Exchange (NSE) officially listed its shares on the Bombay Stock Exchange (BSE) this Thursday. This milestone is notable not only because NSE is India’s largest stock exchange, but also because it is debuting on a platform operated by its longtime competitor. The listing was mandated by regulations, underscoring the evolving structure of India's capital markets.




The NSE's journey began at a time when the Bombay Stock Exchange dominated the country's financial landscape. Founded 34 years ago, the NSE emerged against a backdrop of liberalization and the need for a stock market that could serve investors nationwide rather than a limited group of brokers. The exchange’s rise was driven by technological innovation and a fundamental overhaul of how stock trading was conducted in India.
Manohar J. Pherwani’s Vision
The origins of the NSE trace back to Manohar J. Pherwani, a prominent figure in India’s financial circles and former chairman of the Unit Trust of India. Known as the “Big Bull,” Pherwani is said to have sought BSE membership for a UTI subsidiary in the late 1980s but was reportedly denied. This resistance was believed to stem from concerns that financial institutions' entry could erode brokers' influence. Similar rejections were rumored for other institutions such as ICICI and IDBI. Although these stories cannot be fully verified, they reflect the broker-controlled nature of the BSE at the time, where membership cards granted both ownership and trading privileges, making entry highly restricted and valuable.
The liberalization wave of the early 1990s intensified demand for new stock exchanges across India. RH Patil, later the founding Managing Director of NSE, recalled that the Finance Ministry faced numerous applications to establish exchanges. Pherwani proposed the idea of a national exchange rather than multiple regional ones, setting the stage for the NSE's creation. In January 1991, the Finance Ministry formed a committee that recommended establishing a computer-linked stock exchange in New Bombay to connect investors countrywide.
Originally, the NSE was intended to complement the existing exchanges by focusing on medium-sized firms, bonds, and debentures, not to directly compete with the BSE. However, the BSE quickly understood that a national computerized exchange could challenge its control, which was largely maintained through limited access and broker monopolies.
Impact of the 1992 Securities Scam and Regulatory Changes
The 1992 securities scam involving Harshad Mehta altered the landscape dramatically. The scandal exposed significant weaknesses in India’s financial markets, including opaque transactions and weak settlement mechanisms. It highlighted the need for systemic reforms and strengthened the case for the NSE's establishment as a modern, transparent alternative.
During this period, tensions grew between the BSE brokers and the Securities and Exchange Board of India (SEBI), which sought to regulate the sector. Broker resistance led to a week-long trading shutdown at BSE in April 1992. This confrontation demonstrated the immense influence of brokers and underscored the necessity for a new institution governed by stricter rules.
The government tasked IDBI with advancing the NSE project. Under chairman S.S. Nadkarni, a team including Ravi Narain, Chitra Ramkrishna, Raghavan Puthran, Ashish Chauhan, K. Kumar, and R.H. Patil undertook the challenge. Patil, an economist with a background at the Reserve Bank and IDBI, was chosen to lead despite limited market experience. He aimed to create a market governed by rules and discipline rather than broker dominance.
Revolutionizing Market Structure and Technology
Patil and his team sought to separate ownership, trading, and management, ending the broker-dominated governance model. Membership was opened through an interest-free deposit instead of costly BSE membership cards, which ranged from 30 to 40 lakh rupees at the time. Additionally, NSE introduced fully electronic trading using a VSAT satellite network, connecting investors across India to a central system in New Bombay.
This system eliminated geographic barriers by allowing traders in cities like Indore or Vijayawada to participate equally, directly matching orders anonymously. The BSE had previously experimented with electronic trading but discontinued it due to resistance from brokers who feared losing their advantages. Ironically, BSE’s rejection of these innovations paved the way for NSE’s rapid growth.
NSE’s operations began with the wholesale debt market in June 1994 and expanded to equities by November that year. By October 1995, NSE surpassed the BSE in equity trading volumes, operating in 48 cities, 32 of which lacked their own exchanges. Daily trading volumes on NSE were roughly two and a half times those of the BSE.
This shift marked a significant change in India’s capital markets, challenging the traditional broker-controlled structure and introducing transparency and accessibility. The NSE’s listing on the BSE after 34 years symbolizes this transformation, reflecting the evolution of India’s stock exchanges from closed communities to modern, technology-driven markets accessible to investors nationwide.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0












Comments (0)