


Syngene Sees Revenue Growth in H2 Supported by Order Book and Zoetis Supplies

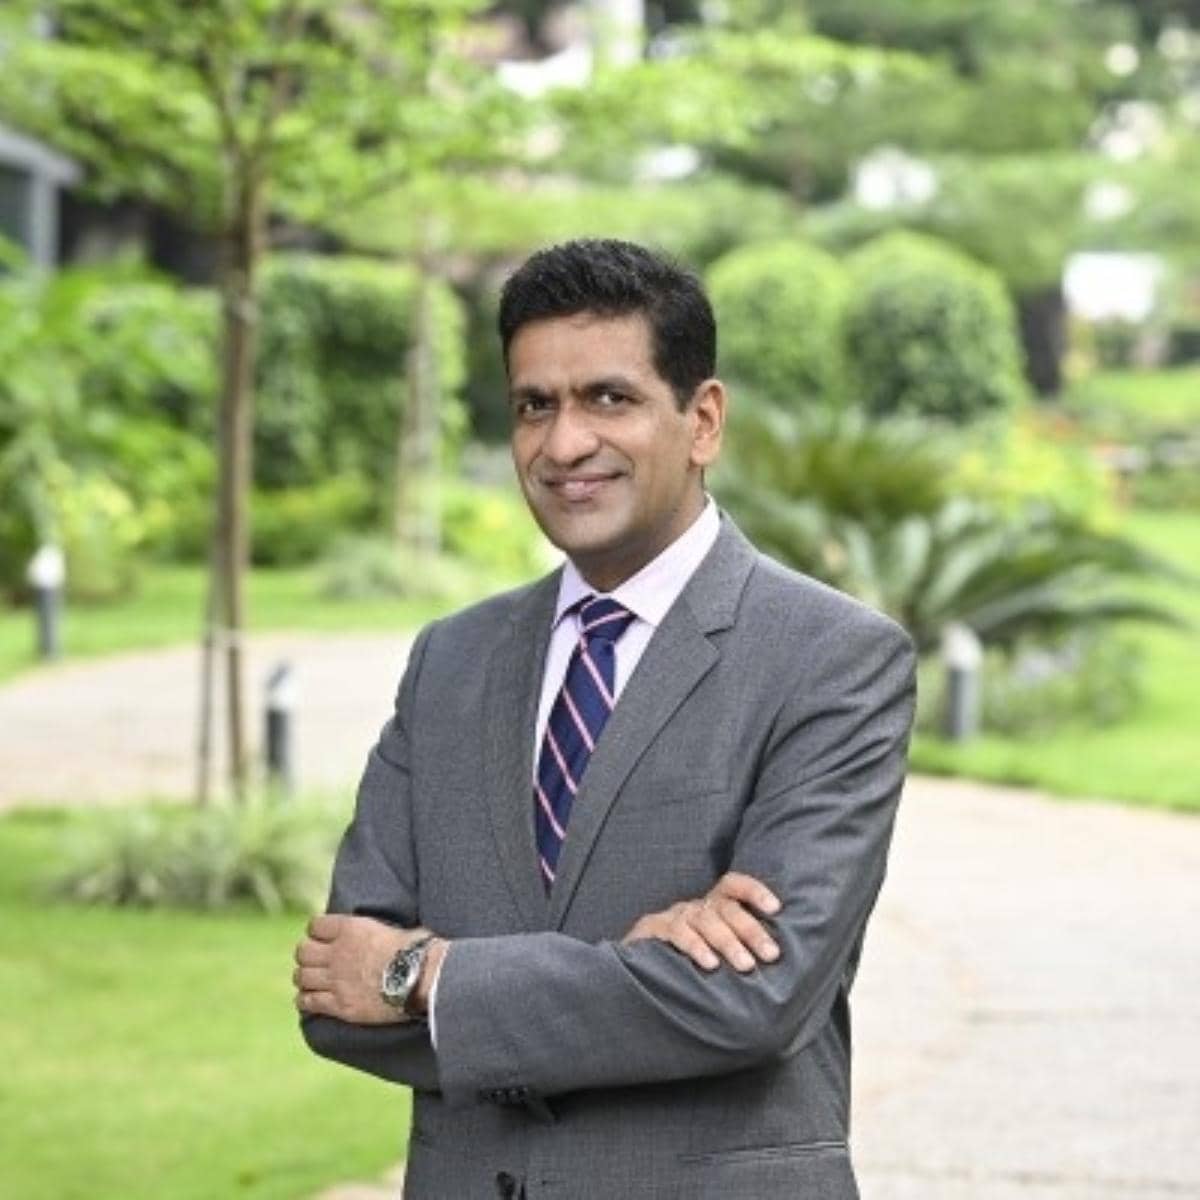


Syngene International projected an improved revenue performance in the second half of fiscal year 2027, citing a solid order book and confirmed delivery commitments from customers. Despite this optimistic outlook for the latter half, the company maintained its full-year revenue forecast, anticipating a single-digit percentage decline compared to the previous year.




In the quarter ended September 2026 (Q2 FY27), Syngene reported revenues of ₹833 crore, marking a 13 percent increase from the ₹736 crore recorded in the first quarter (Q1 FY27). However, this figure was still 9 percent lower than the ₹911 crore reported in the same quarter a year earlier. The sequential revenue gain was primarily driven by positive momentum in Syngene’s contract development and manufacturing organization (CDMO) segment.
Profit after exceptional items reached ₹32 crore in Q2 FY27, a significant turnaround from a ₹9 crore loss in the previous quarter. Siddharth Mittal, Managing Director and Chief Executive Officer, expressed confidence in the second half of the fiscal year, stating, "H2 will be stronger than H1." He highlighted the strong visibility from the current order book and pointed to upcoming supplies for Zoetis, a global leader in animal health, as a key growth factor for the fourth quarter.
Syngene entered a 10-year partnership with Zoetis to manufacture the active drug substance for Librella, an animal health medication. The year-on-year revenue decline partly reflected the absence of Librella-related sales this quarter, which had contributed significantly in the previous year. After completing the scheduled supplies to Zoetis in Q4, Syngene anticipates a pause in Librella manufacturing for an extended period, resulting in some idle biologics production capacity.
To address this gap, the company plans to diversify its biologics offerings by onboarding several products and clients rather than relying on a single major contract. Mittal noted that when Librella is excluded, the CDMO business actually demonstrated growth, while including it resulted in flat performance.
The company’s operating earnings before interest, taxes, depreciation, and amortization (EBITDA) margin improved to 18 percent in Q2 FY27, up from 12 percent in the preceding quarter. Nonetheless, this margin remained lower than the 22 percent recorded in the corresponding quarter a year ago. Mittal attributed the year-on-year margin pressure largely to hedge losses on some large, dedicated center contracts. Syngene indicated that excluding these hedging losses, EBITDA margins would have been in the mid-20s percentile range. These losses are expected to phase out within the next 18 to 24 months, with the company’s updated hedging strategy designed to prevent similar setbacks in the future.
Looking ahead, Syngene views biologics manufacturing as its principal growth area. The company operates 50,000 liters of bioreactor capacity distributed across facilities in India and the United States. Mittal emphasized the growing opportunity as global pharmaceutical manufacturers seek to diversify their production locations away from China, driven partly by regulatory developments such as the US BioSecure Act. He remarked, "That’s where I feel that over the next couple of years, what will drive the growth."
Syngene’s Bayview manufacturing site in the US is preparing to support this expansion. Its initial contract involves development activities in Bengaluru, followed by technology transfer and process scale-up to support regulatory filings. The Bayview facility aims to produce three to four filing batches during FY28. However, meaningful commercial revenue from this site is expected to take longer, contingent on regulatory approvals and product launches. The company will also seek additional customers to fully utilize this capacity.
On the cost front, Mittal reported that manpower rationalization efforts are nearing completion, with expected benefits to begin showing from Q3 FY27. This restructuring included right-sizing teams, particularly within the discovery segment, in response to client losses.
Capital expenditure totaled ₹200 crore in the first half of FY27. The company anticipates increased spending in the second half, including commissioning the first phase of the Bayview facility this quarter. Investments will also target upgrades to existing plants, greater laboratory automation, and enhanced artificial intelligence capabilities to support research and manufacturing efficiency.
Syngene’s strategic focus on biologics and diversified CDMO services positions it to capitalize on shifting industry trends, including increased demand for outsourcing and geographic diversification in pharmaceutical manufacturing. While the current financial year presents some challenges, the company’s pipeline and infrastructure development suggest a stronger growth trajectory beyond FY27.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0













Comments (0)