
SIP or Lump Sum: Investment Strategies in a Sideways Market

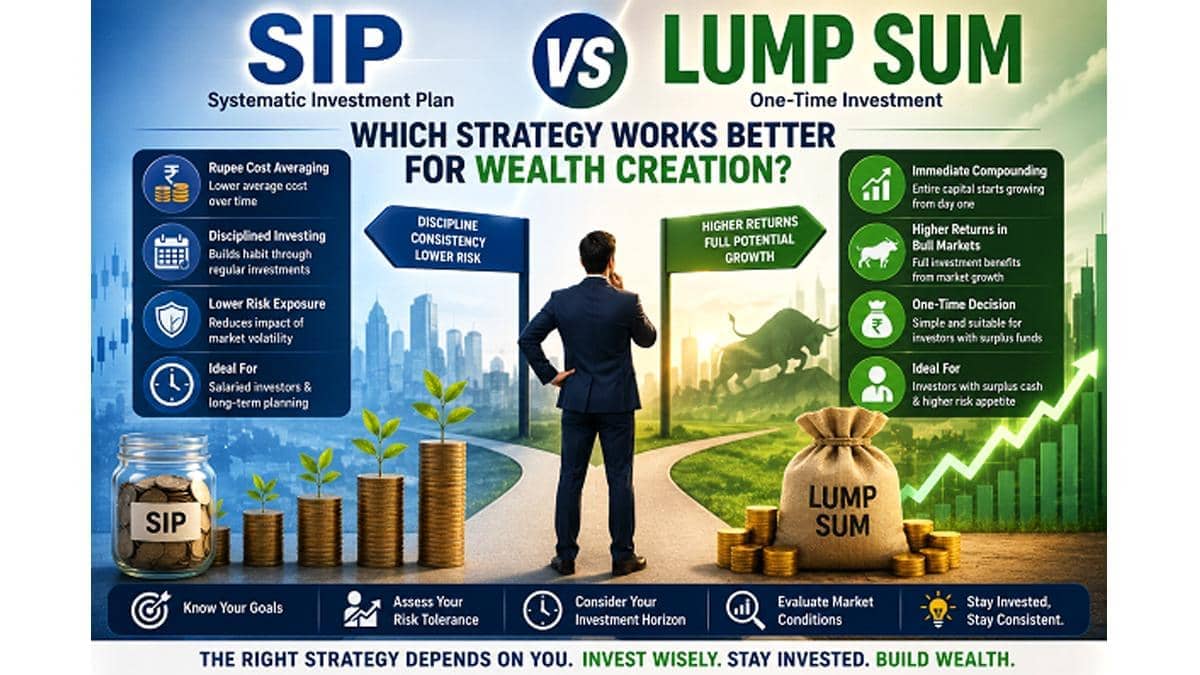
Indian retail investors continue to demonstrate strong confidence in mutual funds despite the Indian stock market facing a period of stagnation. Recent data shows that monthly Systematic Investment Plan (SIP) contributions reached a record ₹32,490 crore in September 2026, reflecting growing participation and maturity among individual investors. However, the market itself has not advanced significantly.
The benchmark BSE Sensex is trading around 14 percent below its peak of nearly 86,000 points reached in late 2025. Throughout October, the index has fluctuated within a narrow band between 71,600 and 74,700 points, indicating a sideways market. This scenario raises a common dilemma for investors holding lump sums from bonuses or matured fixed deposits: Should they invest the entire amount immediately or spread it over time?
Rishit Shah, a Qualified Personal Finance Professional and founder of Vitta Mitra LLP, notes that investors with sound financial plans rarely have unallocated surplus cash. Additional funds typically come from salary increases or bonuses, making the decision on how to deploy this capital crucial.
The Investment Math Versus Market Risk
Historically, investing a lump sum upfront has proven advantageous on average. A 2023 Vanguard study analyzing MSCI World Index data from 1976 to 2022 found that lump sum investments outperformed staggered plans about 68 percent of the time over a one-year horizon. This is primarily because equities generally appreciate over time, and cash held back from investing can miss out on returns.
However, the advantage of lump sum investing diminishes during market downturns. In the worst 5 percent of one-year periods, an all-equity lump sum investment of ₹1 lakh dropped to approximately ₹83,000, whereas spreading the same amount over three months resulted in a slightly smaller loss, falling to around ₹86,000.
Analyzing SIP Versus Lump Sum in Sensex Investments
Looking at historical Sensex data up to October 21, 2026, a monthly SIP of ₹5,000 compares with an equivalent lump sum investment as follows:
- 1 year: SIP value ₹56,358 vs. Lump sum ₹52,259
- 5 years: SIP value ₹3,20,892 vs. Lump sum ₹3,68,642
- 10 years: SIP value ₹9,26,243 vs. Lump sum ₹15,82,800
- 20 years: SIP value ₹34,10,833 vs. Lump sum ₹68,53,098
These figures, based on the Sensex price index excluding dividends and before taxes, reveal that over shorter periods the SIP method may cushion losses by purchasing more units when prices dip. However, over longer terms, lump sum investing tends to yield higher returns due to immediate full exposure to market gains.
Expert Insights on Investment Timing
Rajesh Minocha, CFP and founder of Financial Radiance, advises that lump sum investments increase market exposure but also the risk of immediate corrections. Spreading investments over three to six months can help mitigate timing and behavioral risks, especially in volatile or sideways markets. He adds that Systematic Transfer Plans (STPs) and SIPs are particularly useful during periods of price fluctuations.
Minocha cautions that a sideways market can only be confirmed after the fact, making it difficult to predict market bottoms. He discourages investors from waiting indefinitely in cash, as this may result in missed opportunities if prices rise sharply.
Shah echoes this view, suggesting that for investors without an ongoing SIP, distributing a lump sum over six to ten months is generally sufficient to manage risk. Ultimately, the choice between lump sum and staggered investment depends on an investor’s risk tolerance and comfort with potential short-term losses.
Systematic Transfer Plans: A Balanced Approach
Many mutual fund distributors recommend using STPs to deploy fresh lump sums. In this approach, the entire amount is initially placed in a liquid or debt fund, which has yielded around 6 to 6.5 percent returns over the past year. Subsequently, fixed monthly amounts are transferred to equity funds over a period spanning three to ten months.
For instance, an investor placing ₹12 lakh into a liquid fund and transferring ₹2 lakh monthly to equities over six months benefits from modest returns on the idle cash before it moves to equities. The interest earned during this period could amount to approximately ₹15,000 before taxes.
It is important to note that each transfer from a debt fund to equity involves redemption, which is a taxable event. Under current regulations effective from April 1, 2023, gains from debt funds are taxed at the investor’s income tax slab rate.
Conclusion
Investors weighing their options in the current market environment must consider their investment horizon, risk appetite, and the market’s unpredictable movements. While lump sum investing has historically offered higher returns over the long term, staggered investments via SIPs or STPs provide a cushion against market volatility. Financial advisors generally recommend balancing these approaches to optimize returns while managing risk.
Disclaimer: The views expressed in this article are those of the cited financial experts and do not reflect the opinions of Business Standard. Readers should exercise their own judgment before making investment decisions.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0





Comments (0)