


When Can I Retire? A 67-Year-Old Big-Box Worker’s Reality Check

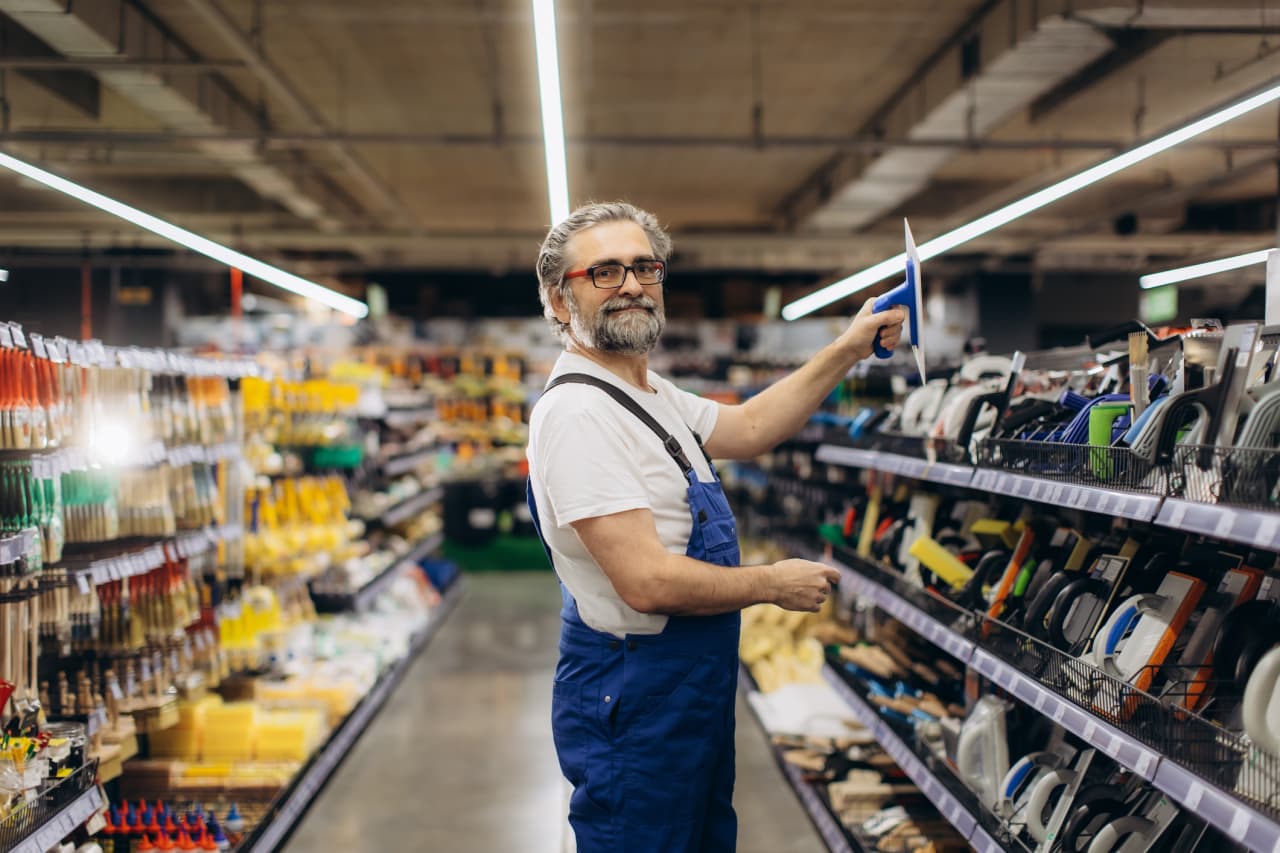


At 67 years old, working on the sales floor of a large retail store earning $19.50 an hour, the prospect of retirement can feel distant and uncertain. For many Americans in similar positions, balancing work, savings, and benefits like Social Security is a complex challenge.




This individual has already begun receiving Social Security benefits at age 66, drawing a monthly amount of $2,410. Alongside this, there is a 401(k) retirement savings account with a balance of $214,000. While these numbers provide some financial foundation, questions remain about how and when full retirement might be feasible without compromising financial security.
Many workers in retail and other sectors with hourly wages face difficulties accumulating enough savings for retirement, especially if their income has been modest throughout their careers. Earnings at $19.50 per hour translate to an annual salary that may not allow for aggressive saving, particularly when faced with living expenses, healthcare costs, and other financial obligations.
Social Security benefits offer a steady income stream, but the amount depends on past earnings and the age at which a person begins claiming. Starting benefits at 66 provides a reasonable monthly check, but delays in claiming beyond full retirement age can increase monthly payments. Conversely, claiming earlier reduces monthly benefits, which may affect long-term income planning.
Having $214,000 in a 401(k) is a significant asset for retirement, but its sufficiency depends on factors like expected lifespan, healthcare needs, inflation, and lifestyle choices. Withdrawals must be managed carefully to ensure funds last through retirement years, especially if other sources of income are limited.
For those still working beyond typical retirement ages, there are trade-offs involved. Continuing employment can provide additional income and allow retirement savings to grow, but physical demands and job satisfaction play important roles. The comment "I don’t want to die on the sales floor" highlights the emotional and physical toll that prolonged labor can have, particularly in roles with active responsibilities.
Financial planners often recommend a combination of strategies to prepare for retirement. These include maximizing Social Security benefits when possible, maintaining disciplined saving habits, managing withdrawals from retirement accounts prudently, and considering healthcare and long-term care insurance options.
Additionally, many retirees explore part-time work or alternative income sources to supplement savings and Social Security. This can ease financial pressures and provide social engagement. However, this depends on individual health and job availability.
Retirement planning remains highly personal and influenced by many variables. For a 67-year-old retail worker earning hourly wages, the path to retirement may require careful budgeting, financial advice, and possibly adjustments to expectations about timing and lifestyle.
Ultimately, understanding the interplay between Social Security, personal savings, and ongoing income is critical. Many Americans face similar dilemmas as they approach or surpass traditional retirement ages without large nest eggs or pensions. Transparent discussions about finances and realistic goal-setting can help in making informed decisions about when and how to retire.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0











Comments (0)