
Rising Gold Loan Defaults Raise Financial Stability Concerns in India

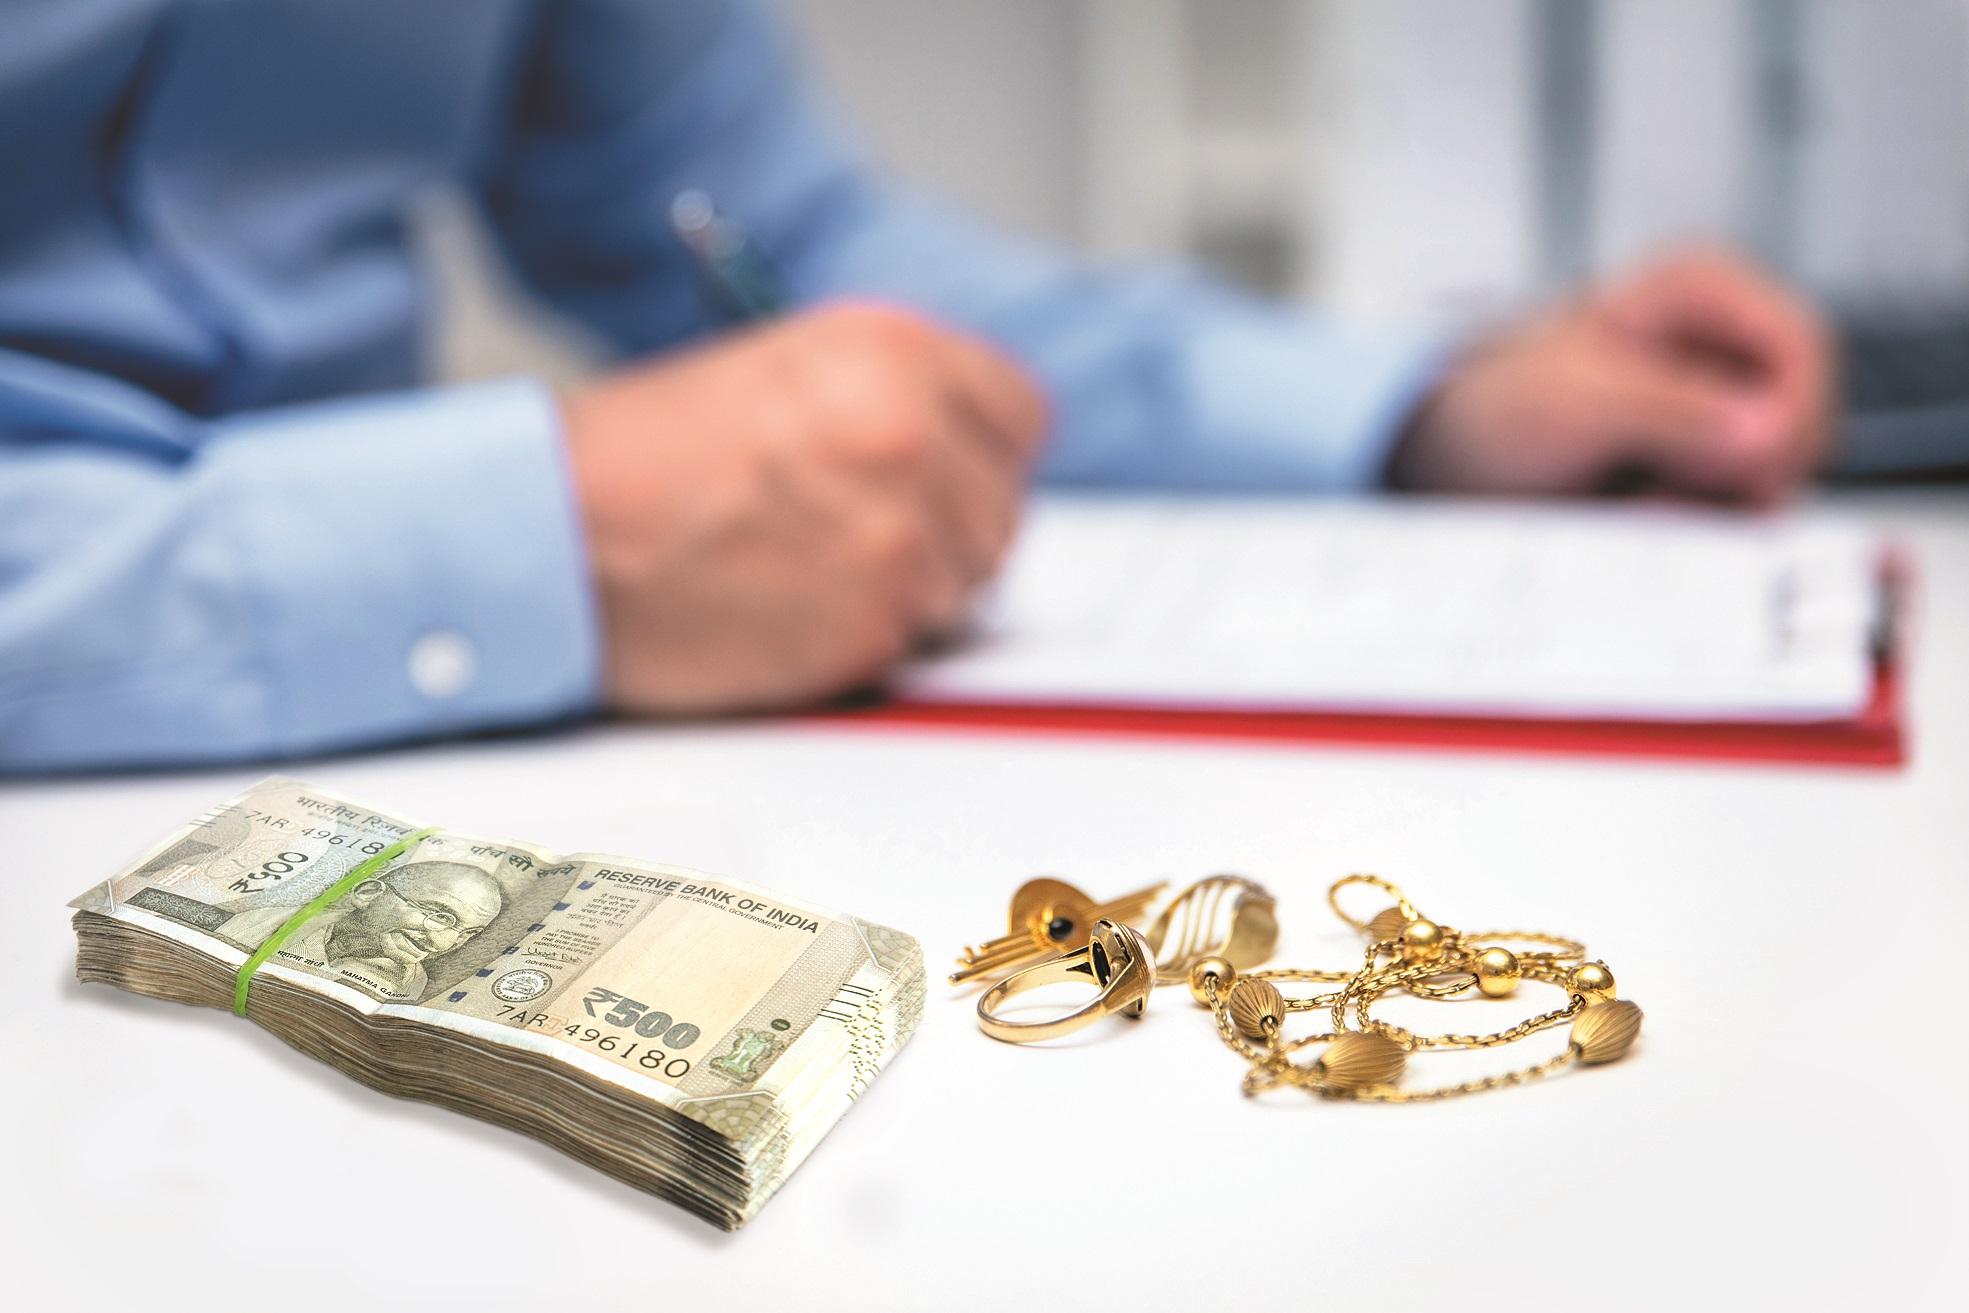
India's expanding gold loan market, a key segment within the country's credit system, is showing early signs of stress that could affect repayment capacity and financial stability. Recent reports have brought attention to a rising number of defaults in this segment, sparking concerns among financial institutions and regulators.
Gold loans function by allowing borrowers to pledge their gold assets as collateral to secure a loan. This system benefits many who otherwise might not qualify for formal credit, as the physical gold backing provides lenders with a tangible guarantee. If a borrower fails to repay, the lender can recover dues by selling the pledged gold. This mechanism has made gold loans a popular choice across various income groups in India.
However, the surge in defaults is testing this model. While the rise in non-performing gold loans does not yet threaten the entire financial system, it signals underlying vulnerabilities. The impact on lenders largely depends on fluctuating gold prices and the specific terms of loan agreements. A decline in gold value can diminish the collateral's worth, increasing risks for lenders and potentially leading to financial losses.
Household debt in India has also been growing, with gold loans contributing a notable share. Many families turn to gold loans to meet urgent financial needs, particularly in rural and semi-urban areas where access to formal banking remains limited. This reliance raises questions about borrowers' ability to manage repayments, especially when economic pressures mount.
India's gold loan market has witnessed rapid growth in recent years, fueled by rising gold prices and increasing consumer demand for quick credit. Non-Banking Financial Companies (NBFCs) and other lenders have expanded aggressively into this space. Yet, the accelerated pace of lending may have led to relaxed credit standards, contributing to the current rise in defaults.
Financial experts suggest that while gold loans offer a convenient borrowing option, both lenders and borrowers must exercise caution. Stronger regulatory oversight and improved risk assessment by lenders could help maintain the sector's health. Additionally, educating borrowers on the implications of default and encouraging responsible borrowing practices are crucial steps to ensure repayment capacity.
This situation reflects a broader challenge in India's credit ecosystem, where balancing financial inclusion with credit quality is an ongoing concern. As the economy evolves, monitoring developments in niche lending areas like gold loans is essential for safeguarding financial stability and protecting vulnerable households from debt stress.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0









Comments (0)