


Bank of India Q2 Profit Climbs 25% to ₹3,202 Cr on NII, Recoveries

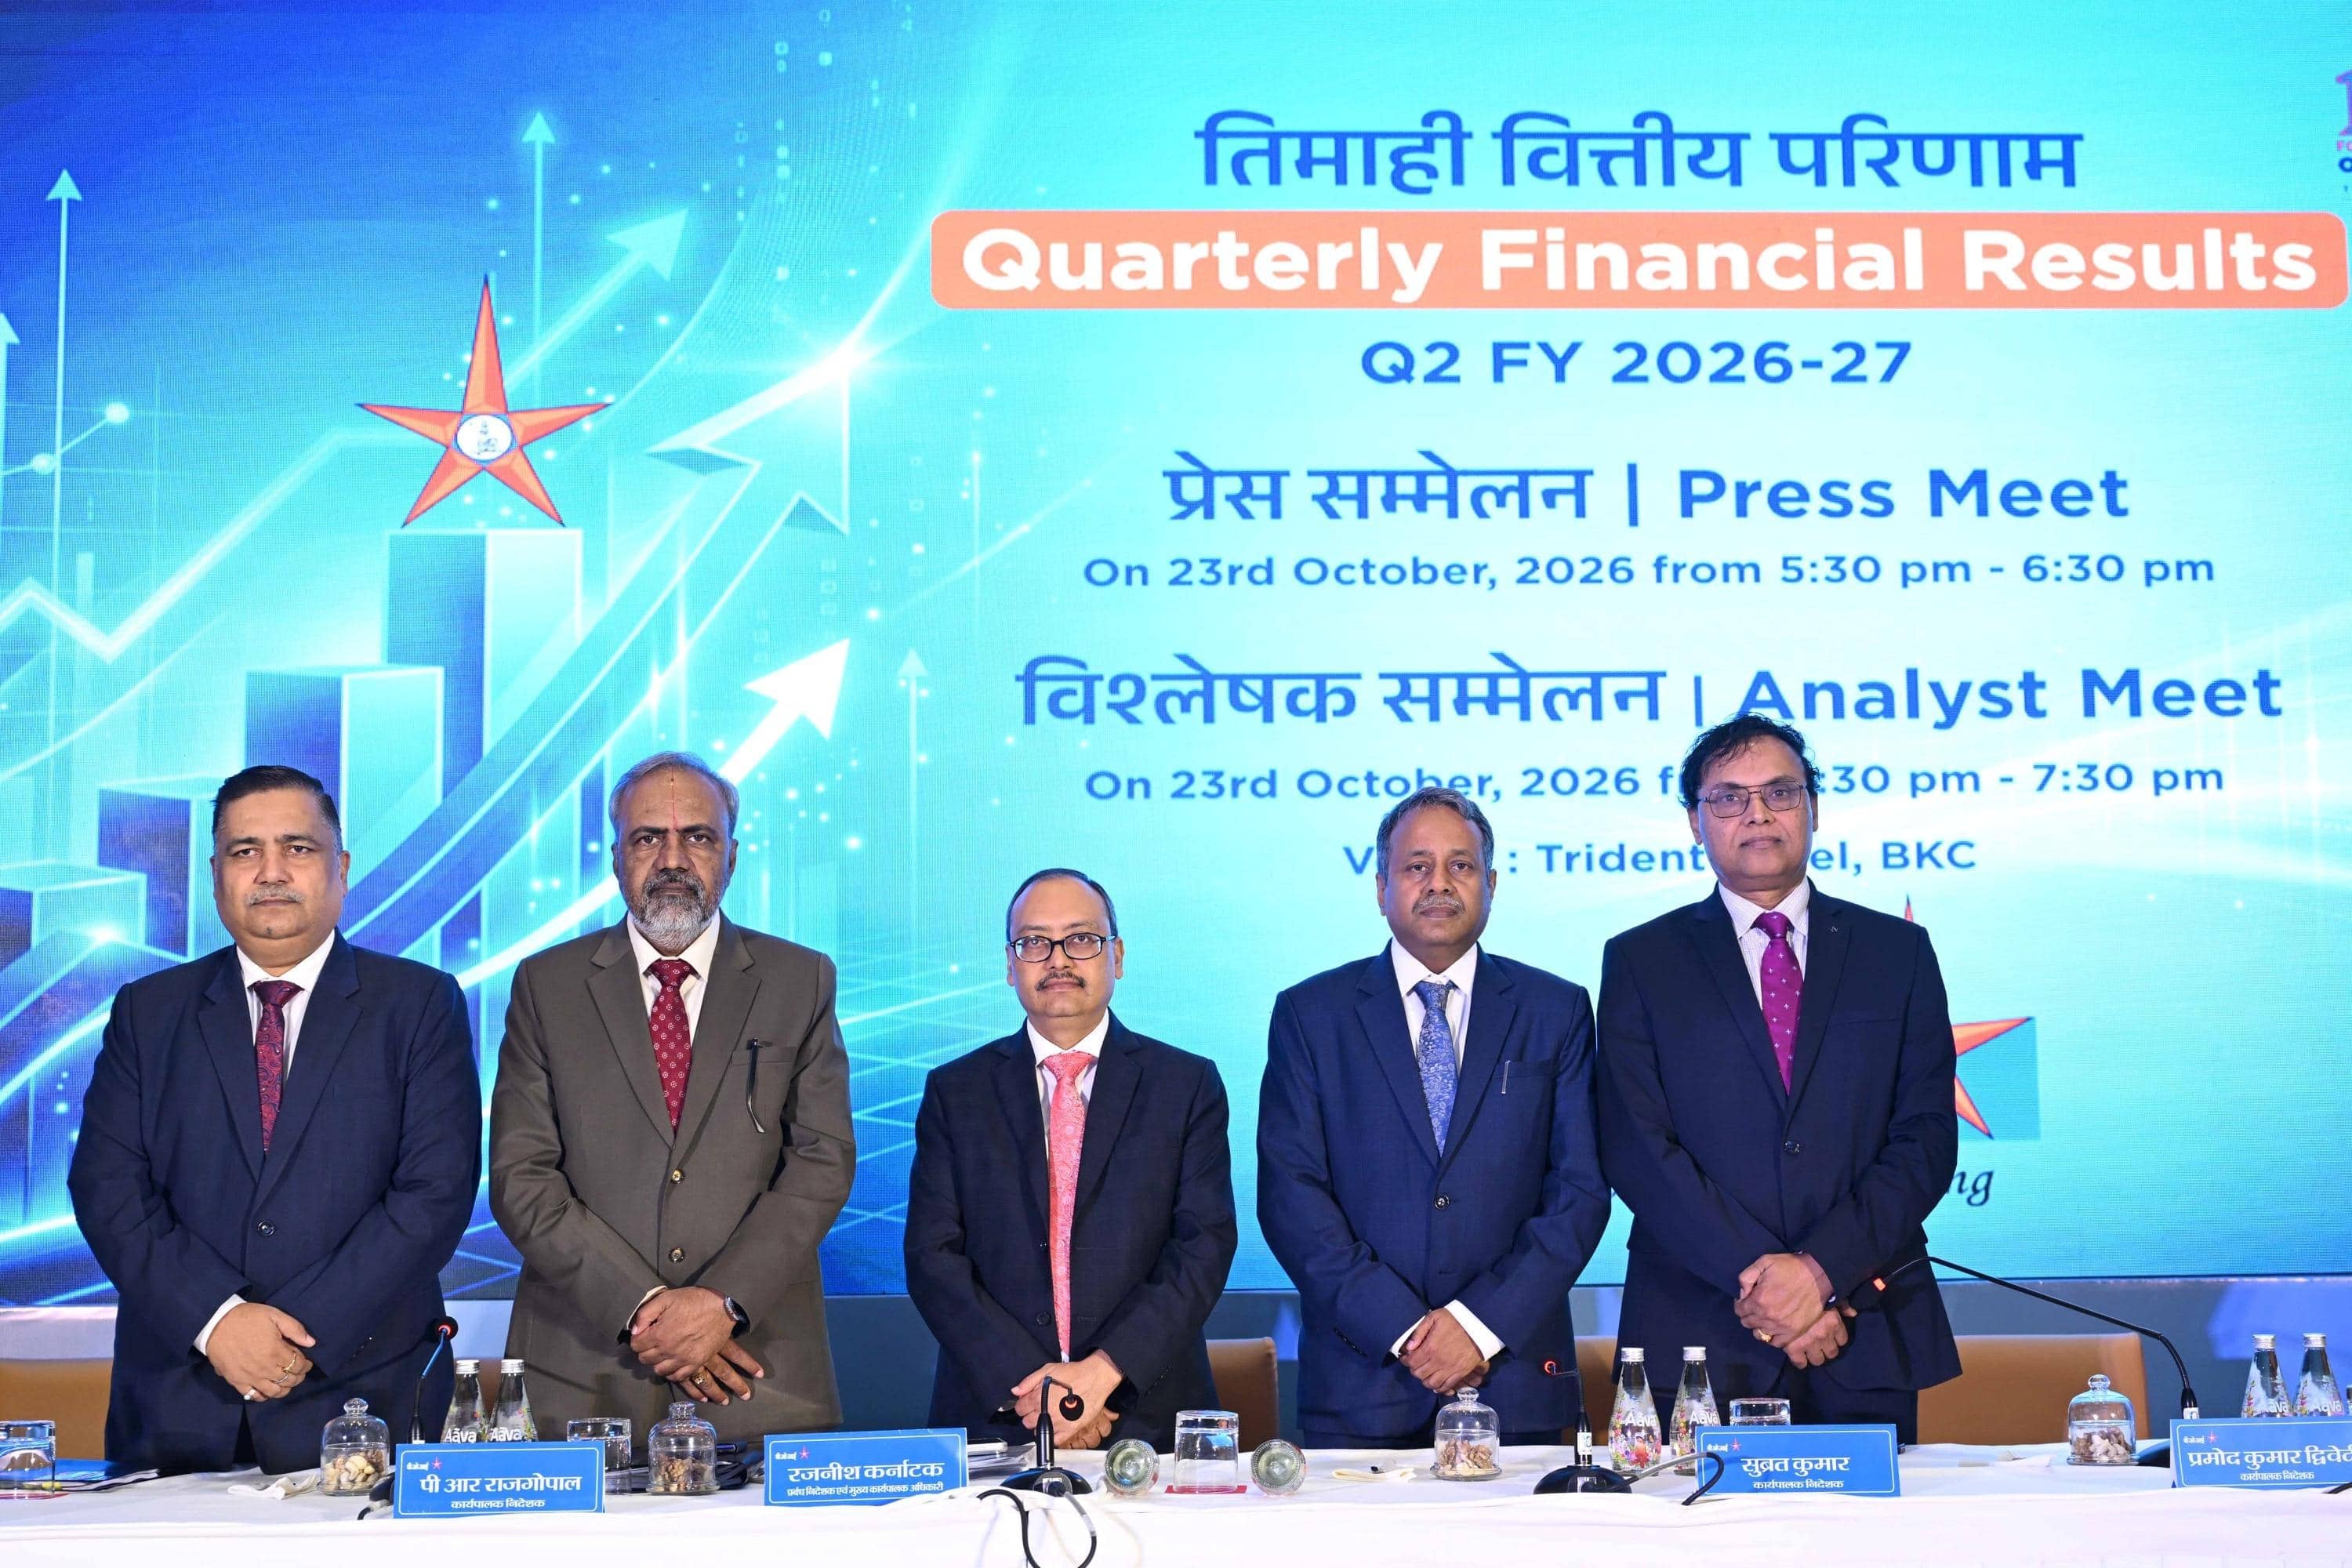


Bank of India, a state-owned lender, announced a 25.34 percent increase in its net profit for the second quarter of fiscal year 2027, reaching ₹3,202 crore. This marks a significant rise from ₹2,555 crore reported in the same period last year. The boost came primarily from a strong growth in net interest income (NII) and a marked increase in recoveries from written-off accounts, which offset declines in treasury income and higher provisioning costs.




Compared to the first quarter of FY27, the bank's net profit edged up 4.37 percent from ₹3,068 crore. For the first half of the fiscal year, Bank of India’s net profit surged by 30.44 percent to ₹6,270 crore, up from ₹4,807 crore during the corresponding period last year.
Non-interest income showed robust performance, rising 24.77 percent year-on-year to ₹2,770 crore in Q2. However, treasury income, which includes gains from the sale and revaluation of investments, fell sharply by 35.99 percent to ₹201 crore from ₹314 crore a year earlier. For the first six months, treasury income dropped 45.77 percent to ₹615 crore.
A notable driver of non-interest income was the recovery from written-off accounts, which soared 190.21 percent to ₹978 crore, compared to ₹337 crore in the previous year’s quarter. Income from exchange transactions also increased significantly by 156.88 percent to ₹411 crore. On the other hand, commission, exchange, and brokerage income declined 4.70 percent to ₹487 crore. Sequentially, non-interest income rose 7.41 percent while treasury income decreased by 51.45 percent from ₹414 crore in the preceding quarter.
Rajneesh Karnatak, the Managing Director and CEO of Bank of India, highlighted the substantial growth in recoveries, stating, "Our non-interest income has reached approximately ₹2,700 crore as of September 2026. The most significant contributor is recovery from written-off accounts, which has increased by more than 190 percent. The bank has made commendable progress in this area, improving from ₹337 crore in September 2025 to ₹978 crore this quarter. There has also been strong growth in profit from exchange transactions, up around 157 percent, from ₹160 crore last year to ₹411 crore this financial year."
On the provisioning front, the bank’s provisions rose 49.05 percent year-on-year to ₹1,887 crore in Q2 FY27 from ₹1,266 crore in the same quarter last year. However, provisions were down 4.84 percent sequentially from ₹1,983 crore in Q1 FY27. The bank recorded a write-back of ₹212 crore on standard assets and others, a significant improvement compared to ₹31 crore write-back in the previous year. Tax provisions increased 31.99 percent to ₹1,089 crore. The credit cost for the quarter stood at 0.12 percent, up from 0.07 percent a year ago but down from 0.15 percent in the previous quarter.
Net interest income grew 18.52 percent to ₹7,007 crore from ₹5,912 crore year-on-year, with a 2.55 percent sequential rise from ₹6,833 crore in Q1 FY27. Interest income climbed 15.34 percent to ₹21,229 crore, driven by a 19.53 percent increase in interest on advances to ₹15,471 crore. Interest expenses also went up by 13.84 percent to ₹14,222 crore. The bank’s net interest margin improved slightly by 6 basis points year-on-year to 2.47 percent but declined 5 basis points from the prior quarter.
Karnatak explained the margin dynamics, noting, "Our overall net interest margin is 2.47 percent, but domestic NIM is above 2.70 percent. Bank of India has a significant international footprint across 15 countries, representing about 15 percent of our book. The international NIM is around 1.14 percent, which lowers the blended global NIM. For the second half of FY27, we expect the global NIM to improve to approximately 2.55 percent."
Asset quality indicators showed continued improvement. The gross non-performing assets (GNPA) ratio fell to 1.60 percent from 1.81 percent in June 2026 and 2.54 percent a year ago. The net NPA ratio decreased to 0.42 percent from 0.51 percent and 0.65 percent, respectively. The provision coverage ratio improved to 94.45 percent from 93.83 percent in June 2026 and 93.39 percent a year earlier.
Fresh slippages during the quarter were ₹1,160 crore, down from ₹1,778 crore in the previous quarter and ₹887 crore last year. The slippage ratio was 0.15 percent. The bank recovered ₹1,635 crore in cash, with write-offs totaling ₹236 crore.
On the business side, global advances grew 20.58 percent year-on-year to ₹8.55 trillion, while global deposits increased 21.59 percent to ₹10.38 trillion. The combined global business expanded 21.13 percent to ₹18.93 trillion. These figures include foreign currency non-resident (FCNR) deposits and advances mobilized under the Reserve Bank of India’s special FCNR scheme during the quarter.
Excluding FCNR-related figures, the bank’s business mix grew 5.44 percent sequentially and 18.48 percent year-on-year. Domestic advances rose 17.84 percent to ₹7.04 trillion. Advances to retail, agriculture, and micro, small, and medium enterprises (MSME) segments increased 18.68 percent to ₹4.13 trillion. Retail loans climbed 19.27 percent to ₹1.74 trillion, MSME advances grew 20.27 percent to ₹1.18 trillion, agriculture advances rose 16.34 percent to ₹1.21 trillion, and corporate and other advances increased 16.67 percent to ₹2.91 trillion.
Within retail loans, home loans expanded 17 percent to ₹85,080 crore, and vehicle loans rose 19 percent to ₹26,349 crore. The domestic current and savings account (CASA) ratio declined to 34.16 percent, down 523 basis points year-on-year and 252 basis points from the previous quarter. The global credit-deposit ratio stood at 82.41 percent, slightly lower than 83.11 percent a year ago.
Bank of India’s capital position strengthened, with the capital adequacy ratio rising to 17.78 percent as of September 2026 compared to 16.69 percent a year earlier. The Common Equity Tier-I ratio also improved to 15.49 percent from 13.89 percent.
The bank’s results reflect steady growth in core income streams and improving asset quality, positioning it well amid a competitive banking environment. Continued focus on recoveries and international operations will be key areas to watch as the bank progresses through the fiscal year.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0












Comments (0)