SBI Q2 Preview: Net Interest Income to Climb 11-13%, Margins Stable
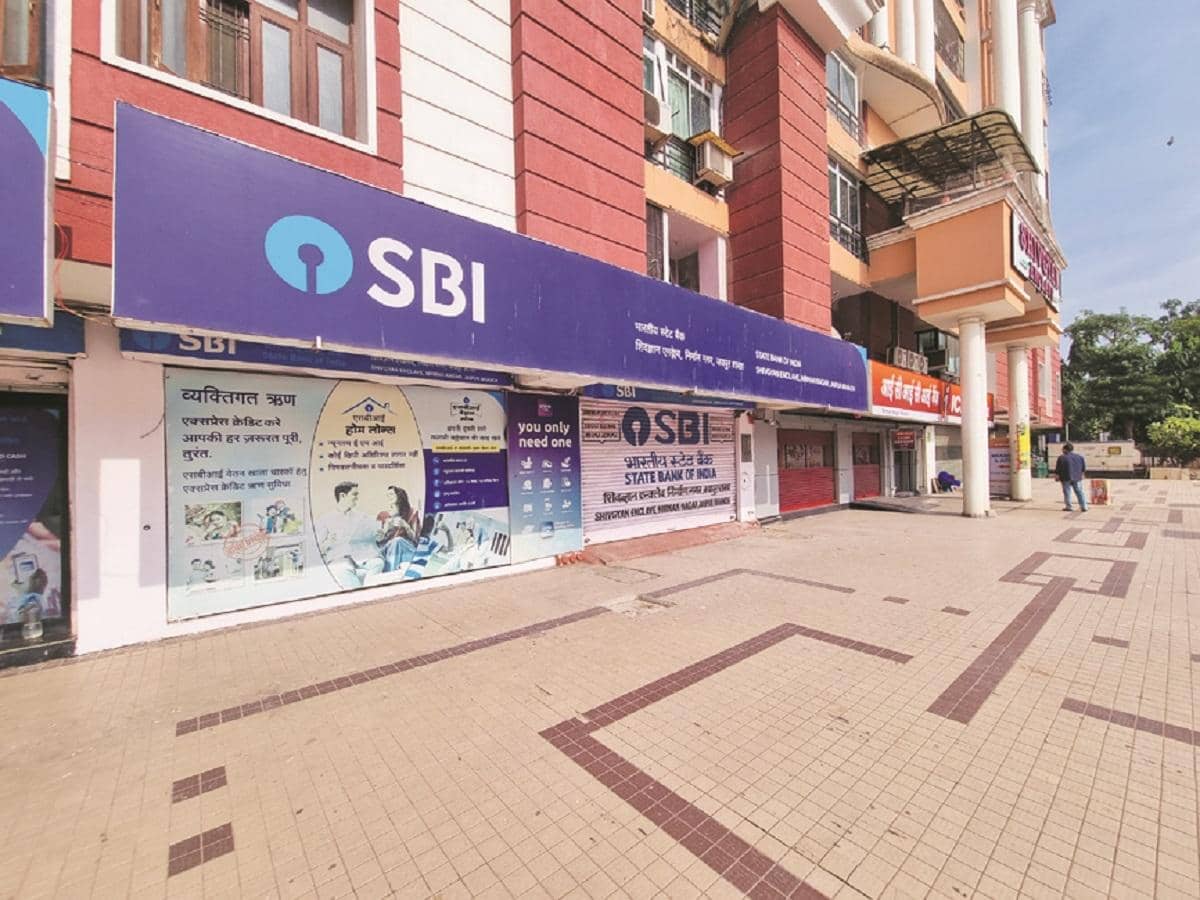
State Bank of India (SBI), the country's largest banking institution, is set to announce its second-quarter financial results on Tuesday, November 3. Industry analysts anticipate that the lender will post an 11 to 13 percent increase in net interest income (NII) compared to the same period last year. This growth is expected to be primarily driven by robust expansion in loan portfolios, while net interest margins (NIM) are likely to remain relatively stable despite a reduction in FCNR(B) deposit inflows during the quarter.
Several brokerage houses have provided previews of SBI's upcoming results, highlighting different expectations regarding profitability and other income components. The outlook includes notable contributions from recent stake sales in SBI Mutual Fund and the National Stock Exchange (NSE), which could bolster the bank's provisions and overall financial strength.
Operating Performance and Margins
Kotak Institutional Equities projects an operating profit growth of about 5 percent year-on-year for SBI, with the profit after tax (PAT) likely to remain flat. The brokerage points to the base effect from the previous year's stake sale in YES Bank as a factor tempering profit growth. Kotak forecasts NII to reach approximately ₹48,573 crore, reflecting an 18 percent increase in loan growth. They expect the bank's net interest margin to hold steady at 2.5 percent sequentially, noting minimal impact from FCNR deposits this quarter.
The brokerage also anticipates slower fee income growth this quarter but factors in gains from the NSE stake sale under other income. Asset quality is expected to remain sound, with low slippage ratios. However, credit costs could vary depending on management’s approach to provisioning, especially regarding expected credit loss (ECL) buffers which have been around ₹3-4 billion in recent quarters.
Projections from Other Analysts
Axis Securities has a slightly different view, estimating NII growth at 11.7 percent year-on-year to ₹48,027 crore. They foresee PAT rising by about 15.6 percent to ₹23,310 crore, supported by healthy advances and deposit growth. Axis highlights the role of stake sale gains from SBI Funds and NSE in strengthening other income. They expect net interest margins to stay stable, with a close watch on any signs of NIM recovery in coming quarters.
Analysts at Axis also predict a modest increase in credit costs and controlled slippage levels, indicating no major asset quality concerns in the near term.
Motilal Oswal Financial Services offers a somewhat more optimistic outlook for SBI's profit growth, expecting a 25 percent increase in PAT during the quarter, alongside an 11.3 percent rise in NII. They forecast a slight sequential dip of 3 basis points in net interest margin to 2.83 percent, attributed to a smaller proportion of FCNR(B) deposits relative to total deposits. Similar to other analysts, Motilal Oswal highlights the positive impact of stake sales on provisioning buffers.
The brokerage expects credit costs and return on assets (RoA), excluding one-off items, to remain steady, signaling stable operating performance.
Context and Market Implications
SBI’s quarterly performance is closely watched given its significant role in India's banking sector and the broader economy. The bank's ability to sustain growth in net interest income while managing margins and asset quality reflects wider trends in credit demand and funding costs. FCNR(B) deposits, foreign currency non-resident borrowings in Indian banks, have fluctuated in recent quarters, influencing the cost of funds and margin profiles for lenders like SBI.
Stake sales in entities such as SBI Mutual Fund and NSE represent strategic moves to unlock capital and improve the bank’s balance sheet. These transactions contribute to other income, providing a buffer that can be used to strengthen provisions or support future growth initiatives.
Investors and market participants will monitor SBI's Q2 results for indications on the health of the loan book, margin trajectory, and credit cost management. This data will offer insight into how India’s largest lender is navigating the current economic environment, balancing growth with prudent risk management.
Readers should note that the forecasts and views cited come from various financial institutions and analysts. These opinions do not represent the official stance of Business Standard, and readers are encouraged to use their own judgment when interpreting the data.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0



Comments (0)