


IBBI Updates Insolvency Rules to Safeguard Homebuyers in Real Estate Cases

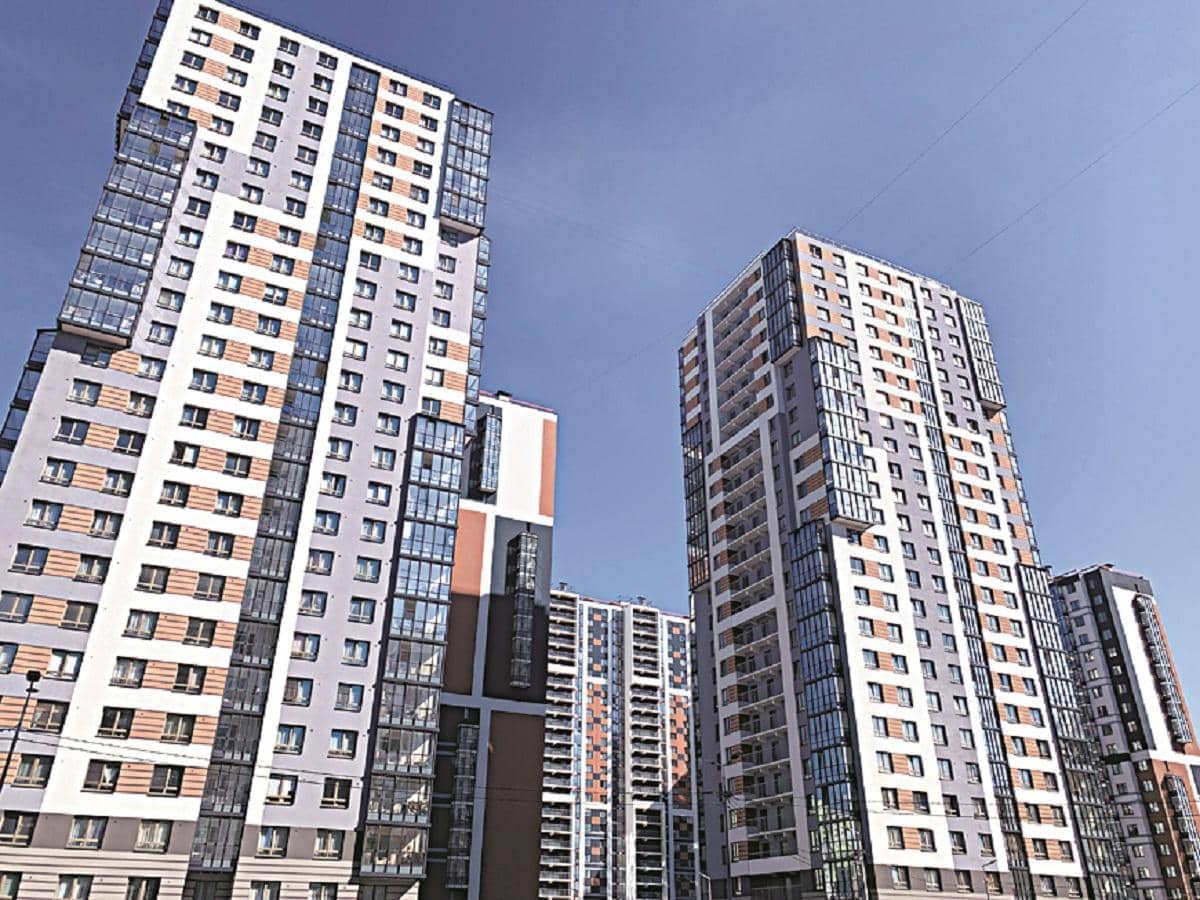


The Insolvency and Bankruptcy Board of India (IBBI) has introduced significant changes to the insolvency framework governing stressed real estate developers. These amendments aim to ensure timely home delivery, strengthen the role of homebuyers in the resolution process, and enable project-specific management, thereby reducing information gaps among stakeholders.




On October 30, 2026, the IBBI issued the Insolvency and Bankruptcy Board of India (Insolvency Resolution Process for Corporate Persons) (Fifth Amendment) Regulations. The updated rules seek to facilitate effective resolution of real estate projects, promote transparency, and safeguard the interests of homebuyers and other parties involved in the corporate insolvency resolution process (CIRP), according to an official press release dated October 31.
These reforms come after a discussion paper published in June that addressed the distinct challenges faced by homebuyers. Unlike financial creditors, most homebuyers primarily want the completion and possession of their homes rather than financial compensation. This unique demand has required tailored regulatory responses to balance interests fairly.
A committee report submitted earlier this year highlighted the ongoing challenges within the real estate insolvency sector. As of September 30, 2025, 221 out of 553 admitted real estate insolvency cases remained unresolved. These cases involved approximately 108,887 homebuyers, representing nearly half of all homebuyers engaged in the insolvency system under the Insolvency and Bankruptcy Code (IBC). The report underscored that many cases had been pending for years, reflecting the sector's complexity and procedural delays in adjudicating bodies.
Under the CIRP, a resolution professional (RP) is appointed to oversee the affairs of the insolvent corporate debtor and manage the resolution efforts. The process is supervised by the Committee of Creditors (CoC), which includes financial creditors such as lenders and homebuyers. Homebuyers participate as a separate class through authorized representatives (ARs), ensuring their interests are directly represented.
The amended regulations clarify that the CoC can approve requests from homebuyers to take possession of completed units, such as apartments or plots, and assist with registration formalities under Regulation 4E. To simplify this process, the CoC may provide an in-principle approval allowing the RP to handle possession requests as they arise, eliminating the need for repeated approvals for each individual homebuyer during the insolvency process.
For developers managing multiple projects, the new rules permit the CoC to recommend excluding specific projects from the resolution process. The RP is required to present detailed project-wise information at the first CoC meeting, including Real Estate (Regulation and Development) Act, 2016 (RERA) registration status, construction progress, possession and occupancy details, and the count of completed and incomplete units. With a minimum 66 percent voting share, the CoC can propose exclusion of certain projects to the Adjudicating Authority (AA), which will then decide on the recommendation.
Enhancing transparency, the amendments require the public announcement of insolvency proceedings to offer creditors a choice among three qualified insolvency professionals designated to act as ARs. Profiles and role descriptions of these professionals must be accessible to creditors to inform their selection.
ARs must submit meeting minutes with their class of creditors to the RP, who will then include these records in CoC meetings. Additionally, the CoC minutes are mandated to document the viewpoints and concerns expressed by ARs, ensuring homebuyers' voices are recorded officially.
The monitoring committee responsible for overseeing the resolution plan's implementation is now required to include the AR or another representative elected by homebuyers. This committee also includes representatives from the relevant Real Estate Regulatory Authority and, where applicable, the competent authority, subject to their consent. Their involvement aims to improve coordination on approvals, compliance, and construction milestones.
Financial discipline has been reinforced by maintaining the obligation, introduced in February 2024, for developers to maintain separate bank accounts for each real estate project. The RP or interim resolution professional must present project-wise financial statements, including receipts and payments, to the CoC at regular intervals while ensuring adherence to RERA's fund utilization rules.
Before inviting expressions of interest from prospective resolution applicants, the RP must secure CoC approval to appoint one or more independent experts to conduct a detailed project-wise technical and cost-to-complete assessment. This evaluation covers construction status, necessary approvals, inventory, estimated costs to complete, funding needs, timelines, and risks. The findings are incorporated into the information memorandum (IM) provided to applicants, enabling informed decision-making.
The IM has been enhanced to include comprehensive details such as project-wise unit inventory, construction progress, common areas, permissible development limits, approvals and their statuses, encumbrances, lender charges, litigation and regulatory proceedings, penalties, complaints, and RERA account balances. It also identifies allottees who appear in developer records but have not submitted claims, listing their names, due amounts, and allotted units. Information about homebuyers' preferences regarding possession, conveyance, registration, refunds, or other remedies, with counts of allottees indicating each choice, is also disclosed.
Resolution plans must specify the number of units sanctioned, constructed, under construction, and distinguish between sold and unsold inventory. These plans must clarify how allottee claims will be addressed, whether through possession, conveyance deed execution, registration, title transfer, refunds, or other methods. They should also outline timelines for completion and possession delivery at the project, phase, or tower level, and provide for regular progress reports to the monitoring committee.
The updated rules require the RP to continue managing the resolution process until the adjudicating authority rules on any withdrawal application under Section 12A of the IBC. Confidentiality protections have been extended to include valuation reports alongside fair value and liquidation value documents.
These amendments reflect the IBBI's efforts to address the complexities of real estate insolvency and improve outcomes for homebuyers, lenders, and developers. By clarifying procedures, enhancing transparency, and promoting project-specific management, the new regulations aim to accelerate project completion and strengthen stakeholder confidence in the insolvency resolution framework.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0













Comments (0)