Volume outlook remains healthy for Ashok Leyland despite margin pressures
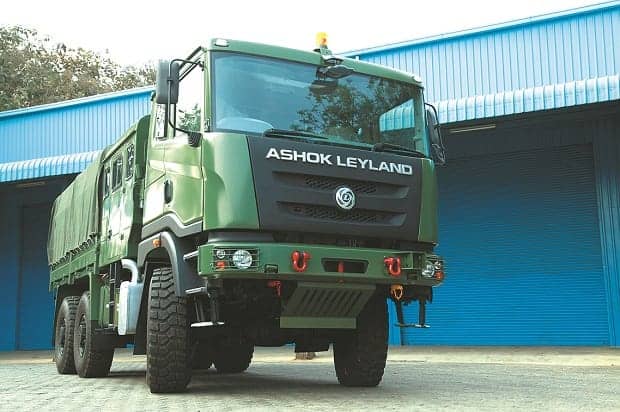
Powered by robust volume growth, commercial vehicle (CV) major Ashok Leyland delivered a better-than-expected revenue performance in the September (Q2FY27) quarter. Even as the topline performance was strong, margins were weighed down compared to the year-ago quarter due to the rise in input costs. The company was, however, able to mitigate cost inflation through multiple measures, including price hikes on a sequential basis.
Ashok Leyland is positive on the demand outlook going ahead and expects the CV sector to deliver a double-digit uptick in FY27. At the current price (₹160.65), the stock, which has gained about 12.68 per cent, is trading at 22 times its FY28 earnings estimates.
The company reported revenue growth of 39.4 per cent YoY, which was ahead of estimates. This was supported by 31.7 per cent YoY growth in volumes, while realisations saw growth of 6 per cent YoY and 5 per cent on a sequential basis. The improvement was broad-based across medium and heavy commercial vehicles (M&HCVs), light commercial vehicles (LCVs) and non-CV businesses. Demand for M&HCVs remains strong on account of replacement demand (ageing fleets), better total cost of ownership for BS6 trucks, higher fleet utilisation, a rise in freight rates and increased spending on infrastructure and construction activity.
Though the base going ahead will be high, the company expects double-digit to mid-teens growth for the CV industry in FY27. The company expects to outperform industry growth on the back of a healthy launch pipeline. The outperformance and market share gains are on the back of an extended HIPPO and TAURUS portfolio (legacy but upgraded heavy-duty truck brands), scaling up the 360-horsepower variants (in Q3FY27) and the addition of air-suspension multi-axle vehicle models.
360 ONE Capital expects FY27 volume growth to be stronger than anticipated, driven by sustained industry momentum, GST-led replacement demand and improving fleet utilisation. Demand is expected to remain healthy in FY28 as well, supported by infrastructure activity and continued fleet replacement, says the brokerage. On the exports front, while volumes in the GCC countries fell 20 per cent in Q2FY27 due to logistical challenges, the company expects a revival in the second half of FY27 as the RAK (UAE) plant nears full capacity. Demand momentum continues to remain healthy in major markets such as SAARC and Africa.
Also Read
Ashok Leyland’s non-CV businesses also registered strong growth, outperforming its CV business. Growth rates for aftermarket, power solutions and defence rose 20 per cent, 33 per cent and 66 per cent, respectively, over the year-ago period. Defence revenue stood at ₹400 crore, and the outlook remains strong given a healthy order book and tender pipeline.
Ashok Leyland has effectively reduced its business cyclicality by focusing on non-truck segments, points out Motilal Oswal Research. Its continued emphasis on margin expansion and prudent capex control should help improve returns in the long run. Further, a net cash position will enable it to invest in growth avenues in the coming years, say analysts led by Radha Agarwalla of the brokerage. The brokerage has reiterated a buy rating with a target price of ₹195.
While overall performance was good, margins remain under pressure. The operating profit margin came in at 10.1 per cent, down 202 basis points YoY. Sharp inflation in commodity prices (steel, natural rubber, fuel and conversion costs) raised material costs by 340 basis points QoQ to 74.9 per cent of revenue, denting margins. The operating profit margin on a sequential basis, however, was flat, aided by price hikes, a favourable mix, cost control and operating leverage. Elara Securities expects input-cost moderation from Q4 and gradual margin recovery thereafter. However, growth for the CV industry should moderate after a strong FY27, implying a modest 3–4 per cent volume growth for Ashok Leyland over FY28–29, says Jay Kale of the brokerage. He has retained a reduce rating with a higher target price of ₹178, up from ₹166 earlier.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0



Comments (0)