Greaves Cotton rallies 9%, stock nears 52-week high; here's why
Greaves Cotton share price movement
Greaves Cotton share price rallied 9 per cent to ₹249.45 on the BSE in Tuesday’s intraday deals amid heavy volume after Ampere reported strong volume growth with its electric two-wheeler (E2W) volumes surpassing full-year FY26 numbers in just seven months in FY27. In the past week, the stock surged 22 per cent.
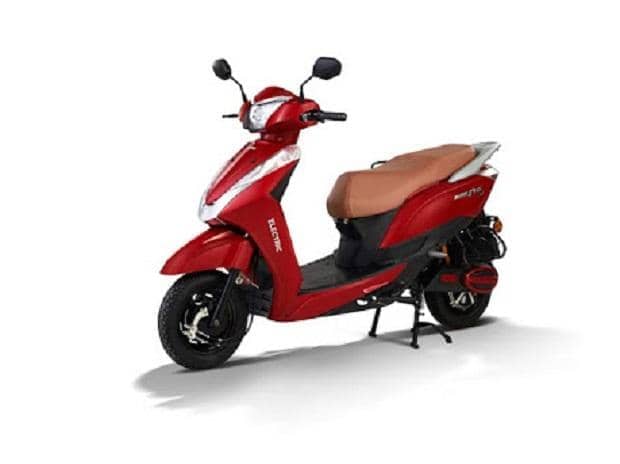
Ampere is the electric two-wheeler brand of Greaves Electric Mobility Limited (GEML). GEML is the electric mobility business of Greaves Cotton and is one of the first companies in India to focus on the evolving market of electric vehicles (EV), having been among the frontrunners driving EV adoption in the country.
At 09:33 AM on Tuesday, Greaves Cotton was quoting 7 per cent higher at ₹244.25, compared to a 0.10 per cent decline in the BSE Sensex. The stock hit a 52-week high of ₹272 on July 14, 2026. The average trading volume at the counter jumped three-fold with a combined 4.8 million shares changing hands on the NSE and BSE.
What’s driving Greaves Cotton stock price?
Ampere continues to accelerate its growth momentum, supported by increasing consumer traction for its products and a growing presence across the Indian electric two-wheeler market.
In FY27, until November 15, 2026, Ampere recorded 70,333 VAHAN registrations, surpassing the 61,842 registrations recorded during the entire FY26. This represents 93 per cent year-on-year growth, compared with 36,452 registrations during the corresponding period of FY26. Ampere reached 5th position with a 5.7 per cent share of the E2W market as on November 15, 2026, Greaves Cotton said in an exchange filing.
Also Read
Meanwhile, in the July to September 2026 quarter (Q2FY27), Greaves Cotton reported strong 44 per cent year-on-year (YoY) growth in its consolidated revenue at ₹1,176 crore. Earnings before interest, tax, depreciation and amortization (EBITDA) increased to ₹73 crore in Q2FY27 up by 43 per cent YoY from ₹51 crore in Q2FY26. EBITDA margins stood at 6.2 per cent, against 6.3 per cent in a year ago quarter.
The management said going forward, the company will prioritise margin recovery, operational excellence and disciplined capital allocation. The company remains focused on translating its growth momentum into stronger earnings, improved return ratios and long-term value creation for shareholders.
Greaves Cotton - India Ratings and Research (Ind-Ra) rating rationale
Greaves Cotton's consolidated EBITDA margin moderated in Q1FY27 at both the standalone and consolidated levels, primarily due to higher raw material costs and investments in personnel, technology, and business development initiatives. However, the management implemented price increases across relevant segments and expects to recover the impact of higher input costs from Q2FY27, with more significant benefits expected in the second half (October to March) or H2FY27. The company’s consolidated EBITDA improved in FY26, supported by stronger performance in its core businesses and a reduction in losses at its electric mobility subsidiary, GEML.
India Ratings and Research (Ind-Ra) expects the revenue growth momentum to continue at 12-16 per cent YoY over FY27-FY28, supported by likely growth across various auto business segments and volume recovery in non-auto applications. The company has also focused on increasing its global presence, through product diversification and inorganic acquisition. In FY24, Greaves Cotton acquired Excel Controlinkage, which manufactures control levers, cables, pedals, and operators, and derives 20 per cent-25 per cent of its revenue from exports, thus expanding the company’s global reach and diversifying its product portfolio, the rating agency said.
Meanwhile, Greaves Cotton is one of India’s leading companies in the 3W engine market with a 55-60 per cent market share. It supplies engines to around 30 original equipment manufacturers in India, such as Piaggio Vehicle Limited, Mahindra & Mahindra, and Atul Auto. The company's ability to maintain such a high market share indicates its competitive edge and relationships with reputed original equipment manufacturers (OEMs), Ind-Ra said. Disclaimer: Views and outlook in this report belong to the brokerages and analysts cited. They do not reflect the views of Business Standard. Readers are advised to exercise discretion.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0



Comments (0)