SBI trades firm in down market, stock up 16% in Nov; brokerages stay upbeat
State Bank of India (SBI) share price movement
Share price of State Bank of India (SBI) traded firm, up 1 per cent at ₹1,118.55. The stock hit an over three-month high on the BSE in Wednesday’s intraday deals in an otherwise subdued market.
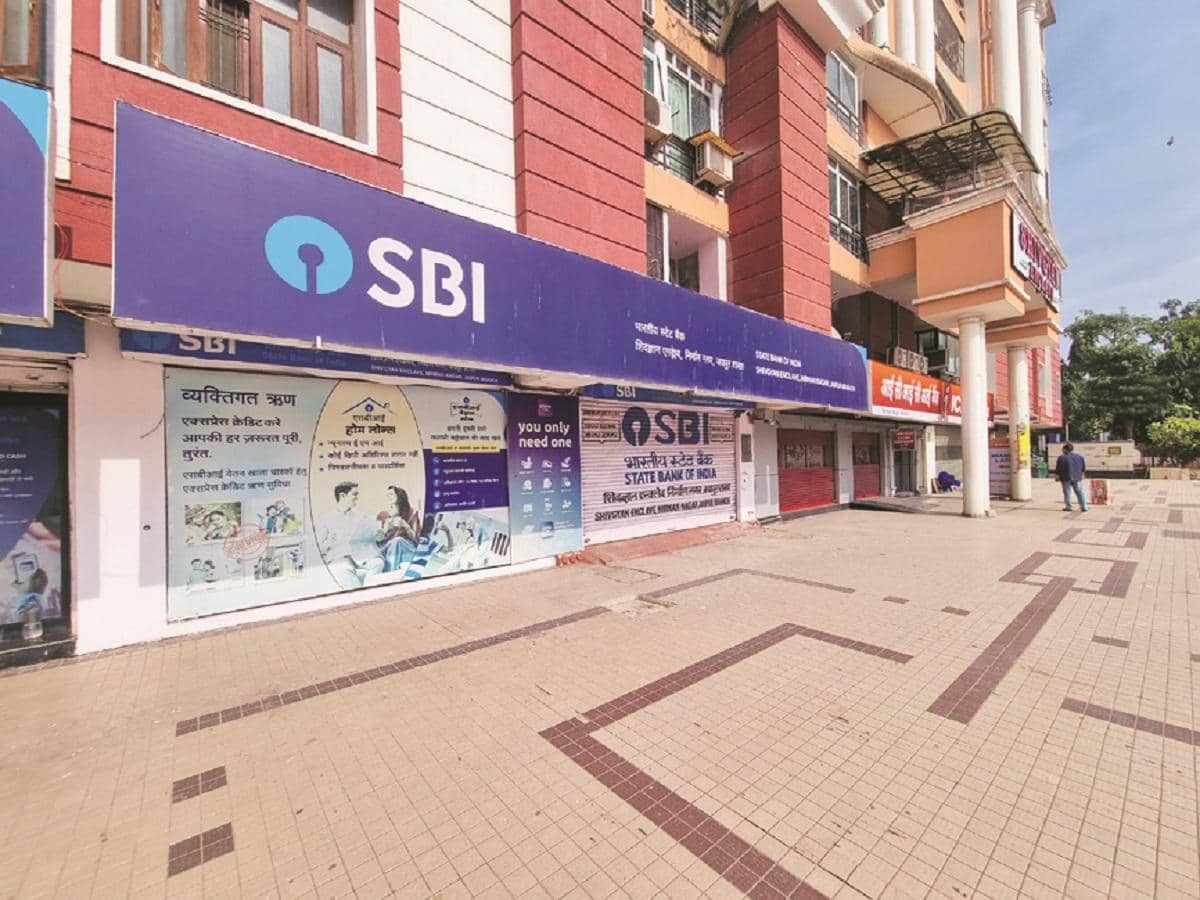
At 11:37 AM, SBI quoted 0.50 per cent higher at ₹1,114.50, compared to a 0.44 per cent decline in the BSE Sensex. The stock of the public sector giant traded at its highest level since August 7, 2026. Share price of SBI stands 10 per cent shy from its record high of ₹1,234.80, touched on February 24, 2026.
Thus far in November, SBI outperformed the market by surging 16 per cent, against a 10 per cent rally in the BSE Sensex.
Here's why brokerages are upbeat on SBI stock
SBI is a public sector bank and the largest bank in India with a balance sheet size of over ₹78.9 trillion.
SBI reported a healthy September quarter (Q2FY27) performance, supported by broadbased credit growth, margin expansion and resilient asset quality, though profitability was aided by one-off gains. Domestic net interest margin (NIM) improved 11 bps quarter-on-quarter (QoQ) to 3.11 per cent aided by lower funding costs, substitution of high-cost wholesale deposits and improved lending yields. Asset quality remained resilient, with the gross non-performing asset (GNPA) ratio at 1.39 per cent, its lowest level in over two decades, while credit cost remained benign at 22 bps.
Also Read
An improving margin outlook, benign credit cost and a comfortable capital position should support a sustainable return on asset (RoA) of ≥1 per cent, though analysts at ICICI Securities see limited levers for meaningful expansion beyond these levels. Factoring in steady profitability outlook and reasonable valuations. The brokerage maintains a 'Buy' rating on the stock with a revised target price to ₹1,200 (earlier ₹1,300) per share.
A slight rise in domestic NIMs to 3.1 per cent was positive; rate hikes & use of surplus liquidity coverage ratio or LCR (140 per cent now) can help the bank deliver 3 per cent plus NIM. Loans rose by 18 per cent, deposits by 12 per cent and asset quality stays robust, according to analysts at Jefferies. The brokerage firm raised the FY27-29 profit estimate by 1-2 per cent. “SBI stays among our top picks with a 'Buy' rating and a target price of ₹1,320 per share.
SBI is one of the best PSU bank franchises, with a strong CASA (current account saving account) franchise, digital-banking platform. The bank has better loan underwriting standards than PSU peers. This has allowed it to maintain better asset quality than its PSU peers. Asset quality trends are strong, with improvement across all segments, while, valuations, though, are attractive, in context of consistent growth in loans and profits, analysts at Jefferies said.
Meanwhile, analyst at Axis Securities also maintain a ‘Buy’ rating on SBI with a target price of ₹1,275 (earlier ₹1,360).
The brokerage firm in its Q2 results update said that SBI’s earnings trajectory is poised to remain buoyant over the medium term, with 1-1.1 per cent RoA delivery emerging as an achievable metric rather than an aspirational target. The strong corporate loan pipeline and improving retail demand should support strong credit growth over the medium term. Focus on profitable growth over margin-dilutive growth, along with benefits of rate hikes accruing and adequate liquidity keeping the cost to deposit (CoD) under control in the near term (while it will recalibrate eventually with the pass-on of rate hikes), provides margin resilience.
Asset quality remains a key strength and at a multi-decadal low, supporting benign credit costs, while the phased expected credit loss (ECL) transition could pose some interim earnings volatility. Thus, SBI’s 1 per cent through-cycle RoA delivery ability remains underpinned by its ability to maintain healthy margins at 3.1 per cent (+/-5bps), contained opex growth with a focus on productivity improvement, and controlled credit costs, analysts at Axis Securities said. Disclaimer: Views and outlook in this report belong to the brokerages and analysts cited. They do not reflect the views of Business Standard. Readers are advised to exercise discretion.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0



Comments (0)