


New Motor Insurance Rules: Mandatory and Optional Cover Explained

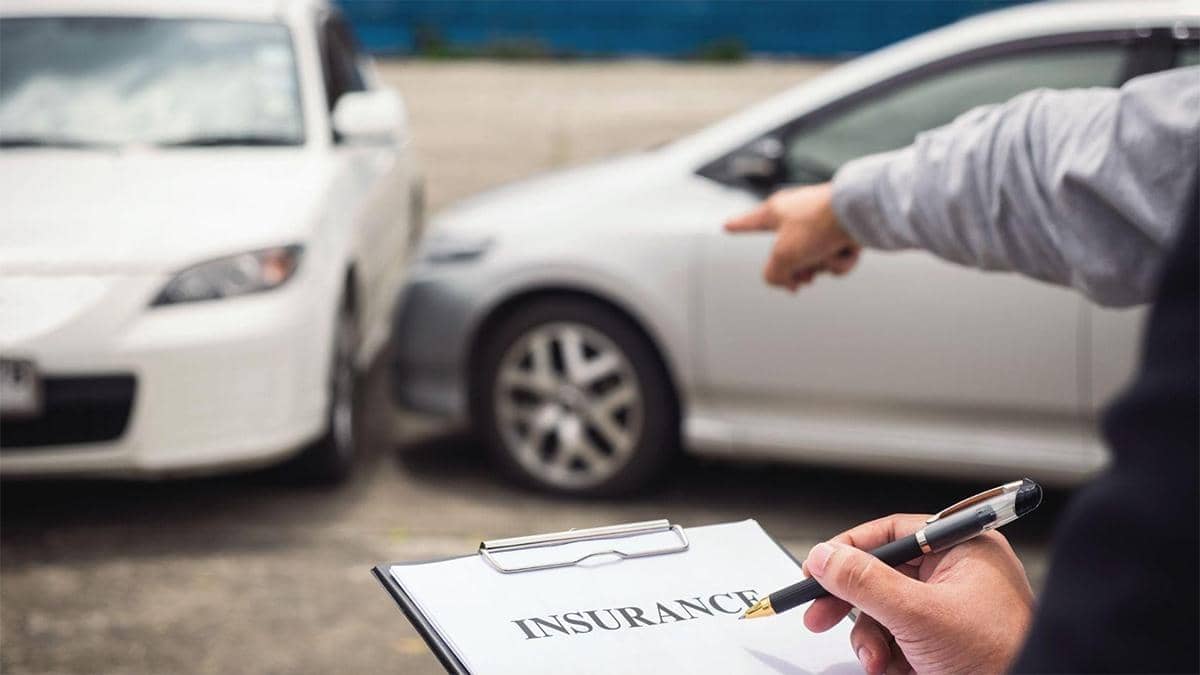


Starting December 15, 2026, individuals purchasing motor insurance for private cars and two-wheelers in India will benefit from a new structured framework introduced by the Insurance Regulatory and Development Authority of India (IRDAI). This system aims to bring transparency by clearly showing buyers the breakdown of costs for mandatory and optional insurance covers, helping them make more informed choices regarding their policies.




The revamped framework divides motor insurance into four distinct layers. While third-party liability insurance and owner-driver personal accident cover remain compulsory, policyholders can now opt for additional protections based on their needs. These optional covers include occupant or pillion-rider liability, personal accident cover for passengers, and own-damage cover that protects the vehicle itself.
At the time of purchase, insurers will provide customers with a standard option form detailing the coverage and premium for each section. This form will become an integral part of the insurance policy, alongside a customer information sheet that summarizes each cover’s premium and scope. This transparent approach makes it easier for buyers to compare policies across different insurers and select the protections that best match their vehicle use and budget.
Legal experts highlight the advantages of this clarity. Raheel Patel, a partner at Gandhi Law Associates, notes that clearly defining passenger coverage at the sale stage will reduce disputes during claims, an issue that has previously led to litigation.
Consumers should exercise caution when considering cheaper policies. Viral Bhatt, founder of Money Mantra, warns that policies covering only the mandatory sections might appear cost-effective but could result in significant out-of-pocket expenses if an accident occurs and the policyholder lacks adequate protection.
The government will maintain fixed premiums for third-party liability, while insurers can set prices for the optional covers. This means that although dropping certain covers might reduce the premium, adding extras such as passenger liability or personal accident cover will increase it. Bhatt explains that the framework itself does not guarantee lower premiums; total costs will depend on the specific coverage selected and insurer pricing.
For those buying insurance after the new rules take effect, experts recommend reviewing the option form carefully. Minoo Mantri, executive vice-president of insurance at Anand Rathi Share and Stock Brokers, advises customers to examine premiums and coverage details under each section before finalizing their choices. Arun Ramamurthy, cofounder of Staywell.Health, emphasizes evaluating the financial risks involved when opting out of certain covers.
People who frequently carry passengers should consider adding occupant or pillion-rider liability and personal accident protections. If any optional covers are unnecessary, customers should ask their insurer to remove them and adjust the premium accordingly, as suggested by Pranjita Barman, partner at Cyril Amarchand Mangaldas.
Maintaining the mandatory third-party cover is essential to comply with legal driving requirements. Additionally, retaining own-damage cover is advisable, especially for newer or valuable vehicles, to ensure comprehensive protection. Ramamurthy recommends reviewing the insured declared value (IDV), deductibles, add-ons, exclusions, and insurer claim service history when choosing policies.
When renewing insurance on or after December 15, 2026, policyholders should reassess all four layers. Factors such as the vehicle’s age, usage patterns, and passenger transport frequency should guide decisions on occupant liability and personal accident cover additions. Barman points out that these covers can be particularly beneficial for those who carpool often, although they do not apply to commercial transport arrangements.
Adding occupant or pillion-rider liability cover midterm is possible by paying an additional premium to the insurer that issued the third-party policy. According to Mantri, the existing third-party cover remains valid, while an endorsement specifies when the new cover takes effect.
To avoid complications, buyers should heed several precautions: do not drop own-damage or occupant covers without carefully considering risks; avoid selecting options without understanding their coverage and exclusions; ensure unwanted default covers are removed; and confirm that any midterm cover additions are active only after the endorsement’s specified date and time. It is also important not to discard key documents like the option form, customer information sheet, policy schedule, or endorsements, as these serve as official records of coverage.
This new motor insurance framework represents an effort by IRDAI to enhance transparency and customization in vehicle insurance. By breaking down premiums and coverage into distinct components, it empowers consumers to tailor policies to their specific circumstances while maintaining necessary legal protections.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0











Comments (0)