


Firecracker Insurance This Diwali: Coverage Details and Buying Advice

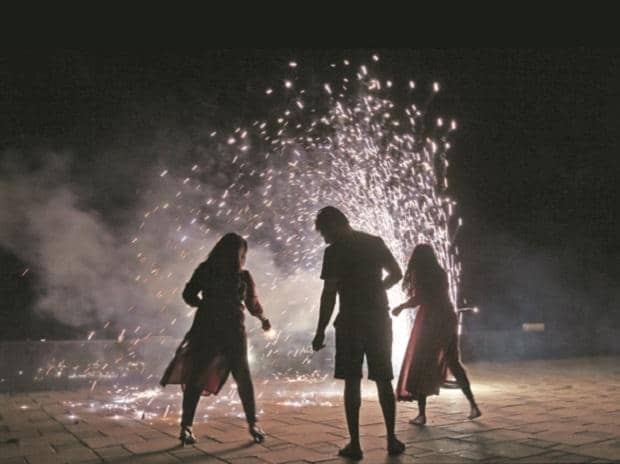


As Diwali approaches, many families prepare to celebrate with traditional firecrackers. While these festivities bring joy, they also carry risks such as burns, eye injuries, accidental fires, and property damage, potentially leading to unexpected financial burdens. In response, several insurance companies and digital platforms have introduced short-term firecracker insurance policies, with premiums starting as low as Rs 11. However, experts advise consumers to carefully review their existing insurance plans before purchasing additional coverage.




Firecracker insurance is a micro insurance product intended to provide limited financial protection against accidents specifically related to firecracker use. These policies typically cover certain medical expenses, hospitalisation, day-care procedures, and accidental death benefits, but they come with relatively low sum insured amounts and are designed to supplement, not replace, comprehensive health or personal accident insurance.
Coverage Details of Firecracker Insurance
Rakesh Kumar, managing director and founder of Square Insurance, explains that standalone firecracker insurance plans usually include coverage for hospitalisation, eligible day-care procedures, burn injuries, and accidental death, depending on the specific product. Medical coverage for burns and related injuries generally falls between Rs 10,000 and Rs 25,000, while accidental death benefits can reach up to Rs 50,000.
Niharika Saigal, head of insurance and in-app categories at PhonePe, adds that these policies are designed to act as a supplement to existing health and personal accident insurance, not as a substitute for more comprehensive plans. One important point for consumers is the limited coverage amounts. For example, a medical cover of Rs 25,000 may provide some financial relief but is unlikely to cover the full cost of severe burns or injuries requiring extended treatment and surgery.
Do Regular Health Insurance Plans Cover Firecracker Injuries?
Consumers often wonder if separate firecracker insurance is necessary when they already have health insurance. Kumar clarifies that most standard health insurance policies cover medically necessary hospitalisation caused by accidental burns, firecracker-related injuries, and eye damage, subject to the policy’s terms and conditions. These injuries are treated as accidental injuries rather than being classified under a special category.
However, it is crucial to distinguish between inpatient and outpatient treatments. Minor burns, outpatient consultations, dressings, rehabilitation, and follow-up care may not be covered unless explicitly included in the health insurance policy.
Rakesh Goyal, director of Probus, emphasizes that health insurance provides the primary financial support when serious injuries from firecrackers require hospitalisation. It can cover costs such as intensive care, surgeries, and doctor fees. Nonetheless, consumers are urged to carefully review policy exclusions, as using banned or illegal firecrackers or engaging in reckless behavior may void claims. Routine outpatient expenses often must be borne by the insured individual.
Example Scenario: Hospitalisation Cost and Insurance Coverage
Kumar illustrates with a hypothetical case of Mr X, a 35-year-old professional who suffers serious burns and an eye injury from bursting firecrackers during Diwali. Suppose his surgery and hospital stay costs Rs 1.15 lakh. If Mr X holds a health insurance policy with a Rs 5 lakh sum insured, and all treatment expenses are admissible, the insurer could cover the Rs 1.15 lakh bill, subject to applicable terms such as exclusions, deductibles, and co-payments.
If Mr X also has a standalone firecracker insurance policy offering Rs 25,000 in medical coverage, this might provide additional financial assistance depending on the policy’s claim provisions. Additionally, if the accident leads to permanent disability affecting eyesight or hand function, a personal accident policy could offer a lump-sum payout based on the disability assessment.
This example highlights why it is crucial for consumers to understand the scope and limitations of each insurance policy rather than assuming one product will cover all financial consequences following an accident.
Should You Purchase Separate Firecracker Insurance?
Experts recommend reviewing your existing insurance coverage before buying a separate firecracker insurance policy. Goyal points out that three types of insurance serve distinct roles against firecracker-related accidents:
- Health insurance: Covers hospitalisation and treatment of serious burns and eye injuries.
- Personal accident insurance: Provides lump-sum payments in the event of accidental death or permanent disability.
- Home insurance: Offers protection against fire-related damage to property and household belongings, depending on the policy terms.
Goyal cautions that festival-specific firecracker policies should not be viewed as replacements for these core insurance covers. It is also important to verify whether property damage and third-party liability are included, as not all firecracker-related losses may be covered.
Saigal adds that short-term firecracker insurance can add an extra layer of financial security during the festive season, especially for individuals lacking sufficient coverage elsewhere. Before purchasing, consumers should check key factors including maximum medical and accidental death benefits, whether hospitalisation and day-care procedures are included, exclusions for outpatient treatments, policy validity periods, and any clauses excluding illegal firecrackers or negligent acts.
In summary, while low-cost firecracker insurance may provide supplementary protection, it should not be mistaken for comprehensive financial security. Ensuring adequate health, personal accident, and home insurance remains the most effective strategy to manage risks during Diwali celebrations.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0










Comments (0)