


Bharat Dynamics shares fall 3% as Q2 margin pressure weighs on earnings

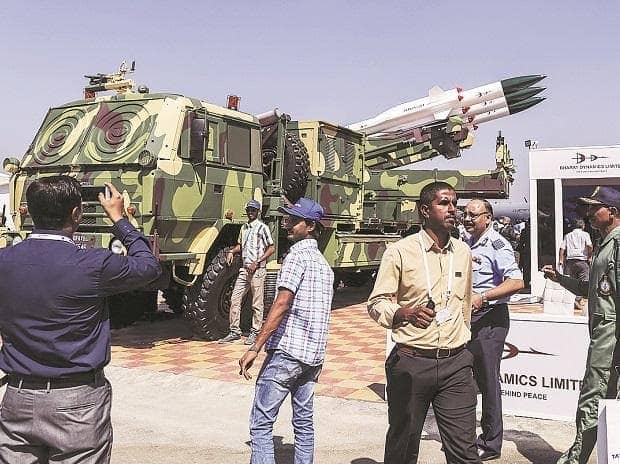


Shares of Bharat Dynamics fell over 3 per cent in intraday trade on Friday after the company reported its Q2FY27 results. MOFSL retained its ‘Neutral’ rating on the stock, citing margin pressure for the company.




The company's counter at 12:21 AM was trading 1.01 per cent lower at ₹1,044.50 per share on NSE. In comparison, Nifty 50 was down 0.7 per cent at 25,104. In intraday trade, the stock fell 3.03 per cent to touch the day's low at ₹1,023 per share.
Bharat Dynamics Q2FY27 result
Bharat Dynamics reported a 45 per cent year-on-year (y-o-y) rise in revenue to ₹1,660 crore in Q2FY27, driven by execution of pending orders for Akash and Astra MK 1 missiles. Profit after tax declined 15 per cent y-o-y to ₹180 crore, while absolute Ebitda fell 46 per cent to ₹100 crore.
The company's gross margin stood at 19.7 per cent, and Ebitda margin contracted 1,020 basis points y-o-y to 6.1 per cent. For the first half of FY27, revenue, Ebitda and PAT rose 60 per cent, 30 per cent and 29 per cent, respectively, to ₹2,240 crore, ₹180 crore and ₹300 crore. Ebitda margin declined 190 basis points to 8.2 per cent.
Also Read
MOFSL on Bharat Dynamics
The brokerage noted that Bharat Dynamics delivered a surge in revenue, driven by execution of pending orders of Akash and Astra MK 1, which were delayed over the past 1-2 quarters. This execution has led to a sharp revenue beat versus MOFSL’s estimate.
However, due to a spike in import content, Ebitda margin contracted both y-o-y and q-o-q it noted. Order inflows were strong for BDL in 1HFY27. “Going forward, with further ramp-up in execution, we expect revenue growth to be strong. However, we now bake in lower margins in our estimates and arrive at our revised target price of ₹1,130 based on a slightly lower multiple of 40 times two-year forward earnings as margin performance continues to disappoint. We reiterate our Neutral rating on the stock,” it added.
MOFSL added that the current quarter’s revenue growth was supported by a spike in the execution of pending projects, which were stuck due to supply chain issues. However, this growth has come at the cost of margins, which stood at 6 per cent for Q2FY27 due to higher import or outsourced content.
Disclaimer: Views and outlook in this report belong to the brokerages and analysts cited. They do not reflect the views of Business Standard. Readers are advised to exercise discretion.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0











Comments (0)