Why the Fed balance sheet is lying to you about the next Bitcoin rally
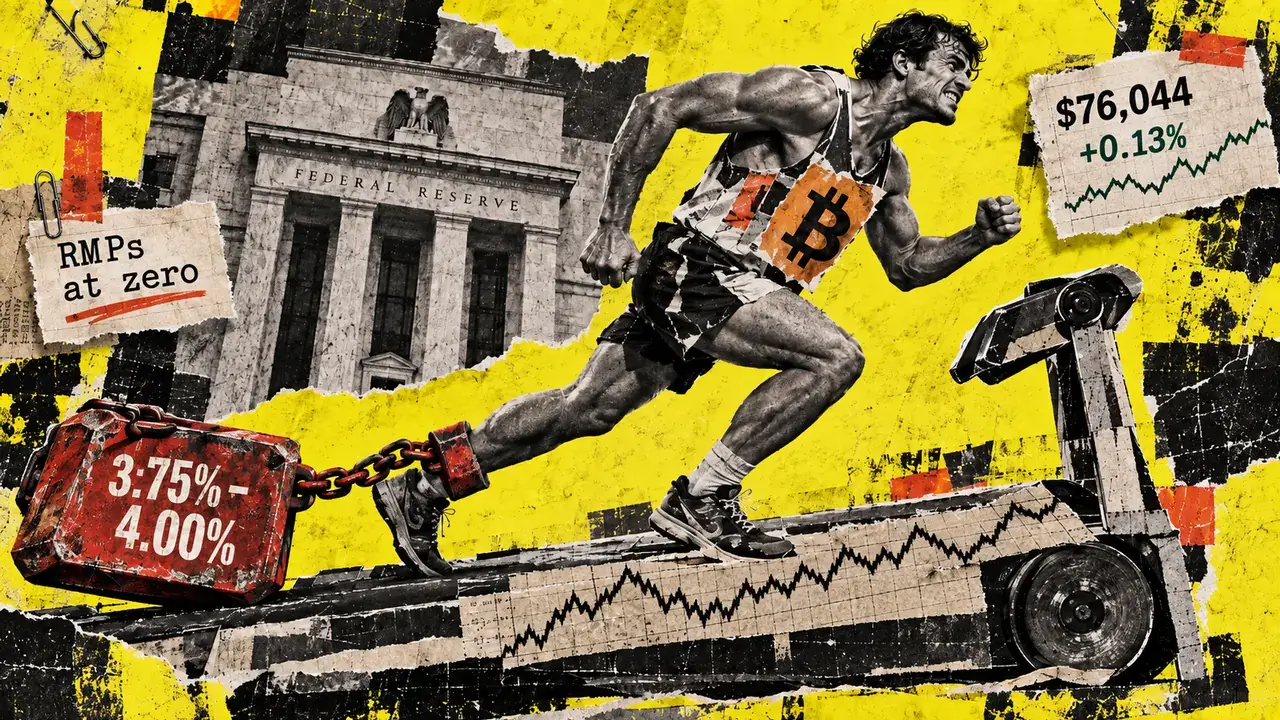
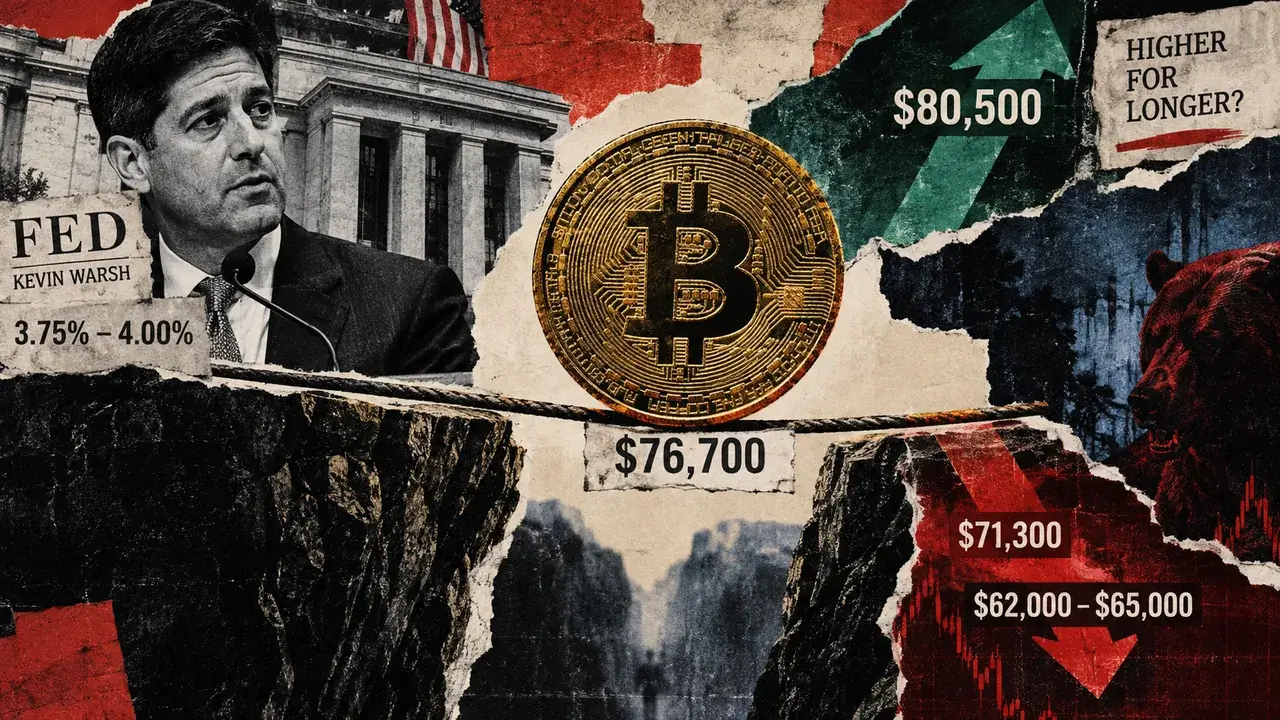
On Sept. 16, the Federal Reserve tightened short-term monetary policy while leaving its reserve-management toolkit in place. The Federal Open Market Committee raised the federal-funds target range by a quarter point to 3.75%–4.00% and continued its policy of maintaining ample bank reserves.
The accompanying implementation directive set the interest rate paid on reserve balances at 3.90%, effective Sept. 17. It also retained conditional authority for the New York Fed trading desk to buy Treasury bills and, if needed, other Treasuries with no more than three years remaining to maintain ample reserves.
Each action serves a separate function. A higher administered rate transmits the tighter target range, while reserve-management authority supports the operating system used to keep overnight rates under control. Bitcoin liquidity depends on how those policies reach financial markets, beyond the size of the Fed's balance sheet.
How reserve plumbing differs from QE
QE is designed to ease monetary policy. It typically uses large-scale purchases of longer-term Treasuries and agency mortgage-backed securities to remove duration risk from private portfolios, press down on longer-term rates and loosen broader financial conditions.
Reserve-management purchases, or RMPs, have a narrower purpose. They add reserves through purchases of bills and other short-dated Treasuries so the Fed can implement its chosen short-term rate as currency, Treasury balances and other liabilities change.
Vice Chair Philip Jefferson made that distinction in January, describing QE as a stimulus tool that removes duration risk and RMPs as an instrument for maintaining ample reserves and effective short-rate control. New York Fed markets chief Roberto Perli separately said the 2026 reserve-management purchases had been entirely in bills and contrasted them with longer-duration purchases used to ease financial conditions.
That division of labor allows Fed assets to rise while the policy stance tightens. Balance-sheet direction records changes in the central bank's assets and liabilities. The purpose, maturity and transmission of the purchases determine what those changes mean for policy.
The September directive continued an RMP framework launched in December 2025, and the New York Fed says the monthly amount is not on a preset path. Its current operations schedule sets RMPs at zero for the Sept. 15–Oct. 14 period. The schedule includes about $15.6 billion of Treasury-bill purchases funded by principal payments from agency securities, a reinvestment flow separate from net RMP buying.
The trading desk retains the capacity to add short Treasuries when appropriate. Its published schedule shows that capacity currently unused for RMPs, sharply limiting claims of an immediate fresh reserve injection.
The earlier purchase totals show why the accounting needs care. Through July 1, the Fed's Monetary Policy Report said the System Open Market Account had bought nearly $250 billion of Treasury bills since early January. About $160 billion came from RMPs and $90 billion from agency-security reinvestments. Over the report's comparison period, total Fed assets rose $151 billion and reserve balances increased $54 billion as other balance-sheet items moved as well.
The latest pre-decision H.4.1 release put total assets at $6.740619 trillion on Sept. 9, up $3.415 billion from the prior week and $134.657 billion from a year earlier. Those figures establish the size and direction of the balance sheet. QE classification instead turns on the purpose and composition of the program.
What the package means for Bitcoin
Bitcoin markets absorbed a quarter-point rate hike alongside the continued ample-reserves framework. The framework is intended to support reserve supply and short-rate control, while the target rate and interest paid on reserve balances moved higher.
The pre-decision money-market readings were consistent with the Fed retaining control of overnight rates. On Sept. 15, the secured overnight financing rate was 3.64% and the effective federal-funds rate was 3.63%, close to the then-current 3.65% interest rate on reserve balances. Overnight reverse-repo take-up was about $0.7 billion.
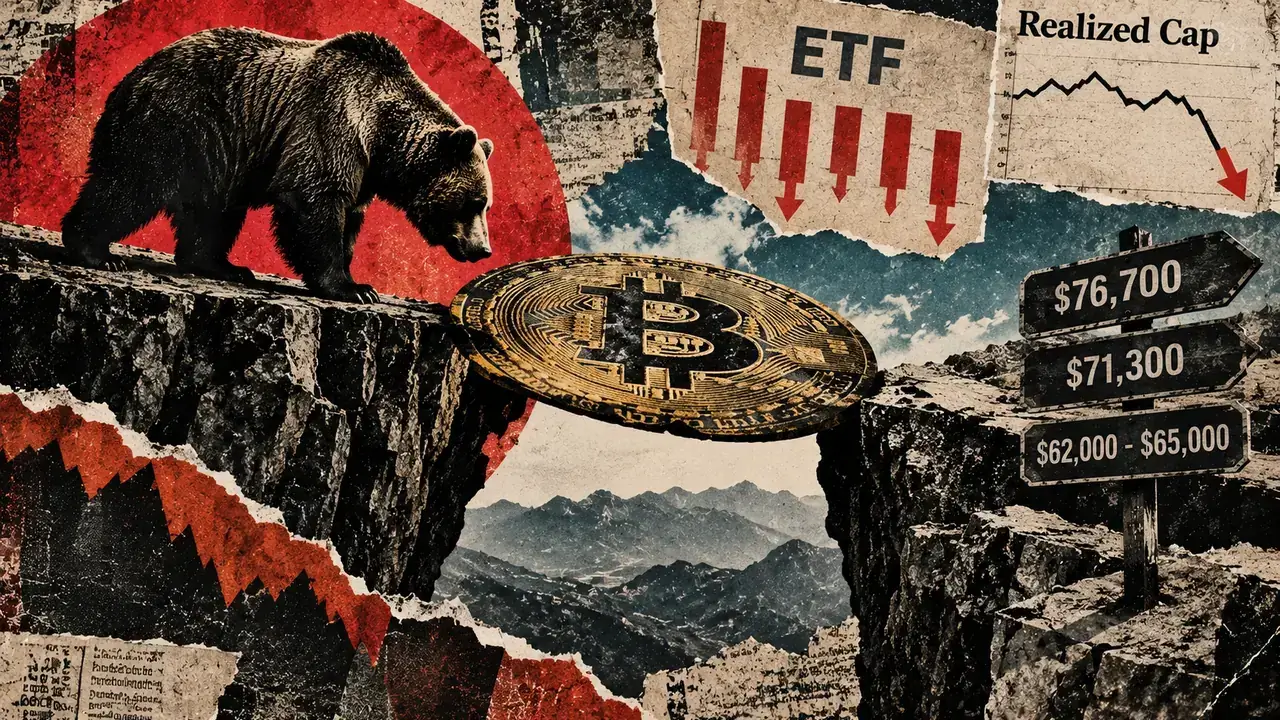
Those funding readings help classify the reserve policy. The crypto-market figures offer contemporaneous context rather than evidence of transmission. CryptoSlate's Bitcoin market data showed the asset near $76,044 with a 0.13% gain over 24 hours, while Farside Investors recorded $450.4 million of net outflows from U.S. spot Bitcoin exchange-traded funds on Sept. 15. Causal attribution to the Fed decision remains unsupported.
Future balance-sheet growth should be judged first by the program itself. The decisive evidence would be its announced purpose, scale and maturity composition, along with whether the New York Fed schedules net reserve-management purchases. A program designed to ease policy by removing substantial duration risk would be materially different from conditional bill purchases used to maintain ample reserves.
Broader transmission still matters to Bitcoin. A convincing liquidity-pivot case would pair easier longer-term financial conditions with stronger crypto demand. Bitcoin prices and ETF flows can reveal investor response, while the Fed program's design determines whether the QE label fits.
For now, the Sept. 16 package is tighter monetary policy implemented through an ample-reserves system. The QE label collapses two separate functions into one balance-sheet number and overstates what the Fed has delivered to Bitcoin.
The post Why the Fed balance sheet is lying to you about the next Bitcoin rally appeared first on CryptoSlate.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0


Comments (0)